Introduction
With the advent of technology, banking has undergone great transformation in terms of how people save, borrow, transfer and manage their finances. In today’s world, users can opt for one of the digital banks, which are not physical banks but function largely online, and/or traditional banks that offer physical branches and online services. A digital-first bank is a financial institution that leverages mobile apps, websites, automation and the streamlined business design to provide financial services without being heavily reliant on physical branches. However, traditional banks integrate digital banking together with their network of branches to provide face-to-face support to their customers. In addition to the ability to provide financial services, the two banking models vary on their availability, cost, customer service, lending and technology. A grasp of these distinctions enables individuals and companies to pick a banking solution that aligns with their monetary goals and their communication choices and preferences, as well as their expectations for security and reliability.
Digital Bank and Traditional Bank
Digital Banks
Digital banks offer the bulk of their banking services via digital platforms, such as mobile apps and online platforms. Consumers can create accounts, view their account balances, move or transfer money, pay bills, get notifications and see the transactions without having to go to a physical branch. Another type of digital financial service providers is neobanks, which are more similar in nature but generally don’t have the traditional banking branch network and are mainly targeted to convenient, technology-driven services. But not all neobanks are licensed banks some enter into relationships with licensed financial institutions to offer payment services and deposit accounts. Digital banks are typically leveraging the automation of their processes and online customer service to cut down on their operating expenses and to ease the typical customer’s daily operations.
Traditional Banks
Traditional banks have physical branches, plus applications, web sites, ATM’s and electronic payment systems. Customers can simply access their bank account online and make regular transfers or payments, and then visit a branch for more complex needs like arranging a mortgage, dealing with some account issues and/or advice on business finance. These institutions may have developed a relationship with customers, a widespread financial product offering and a wide network of service providers. They can help calm people who like to discuss matters with the representatives of the financial institution. However, there are other costs associated with running a branch, such as those for rents, utilities, staffing and maintenance. For traditional banks, these costs are a challenge to reconcile with investing in digital solutions to compete with new fintech firms and ensure they can deliver services to customers who prefer to use traditional banking channels.
Differences between Digital and Traditional Banks
The Policy is Implemented on the Website.
It may also be possible to open an account with the digital bank via a mobile app or website. Applicants can upload identification papers, personal information, photos and other necessary information electronically. The process can be expedited by automated verification, though there is a time lag that varies according to the provider, the check of the identity and the regulatory requirements. Some traditional banks also allow you to open a bank account online, although others may have certain requirements for the account (such as a visit) and may require additional documentation. Their branches still have value to customers requiring help filling out forms and/or identification issues. Traditional banks might be more suitable for customers who are in need of face-to-face assistance or who have frequent need to access services at physical locations, and digital banks are more convenient for customers who value the ability to access services remotely.
The Customer Support and Customer Service Quality
There are also some differences in customer support between these banking models. The common methods of providing support to digital banks are in-app messages, email, telephone, chatbots and online help centres. These channels can simplify the reporting of transactions and the ability to ask questions or get auto-updated information, without a trip to a branch. But, when there are important issues that need to be addressed, customers can get agitated when they do not receive human assistance and support within a reasonable time period. Traditional banks might provide you with a better choice, including phone support, appointments at a bank branch, or speaking directly with the banking personnel. Service still varies from one institution to another and a visit to a branch does not necessarily ensure that a problem is solved. Purchasers should look at the support hours, complaint methods, emergency call numbers and the availability of skilled representatives prior to picking a provider.
Fees and Operating Costs
Digital banks can have lower account fees, fewer minimums and even competitive transaction fees that are lower than traditional banks due to the lack of physical branches. Some providers will provide very good rates of interest, or lower fees to draw in customers. But free digital banking isn’t a right of any kind. There are possible ATM withdrawal fees, foreign exchange mark-up fees, transfer fees, overdraft fees or premium subscription fees which may be charged to customers. Most traditional banks offer inexpensive or free checking accounts, but some banks may require a minimum amount to prevent fees or may charge fees for account maintenance. The pricing may also vary by accounts and eligibility of the customers. Customers need to review the total fee structure, including fees for transfers, replacement cards, cash withdrawals, international transactions, and being inactive in their account prior to opening an account.
Savings Products and Interest Rates
Banks can offer both models of accounts with savings, but the range of products and the terms of their offer vary. Because digital banks have many of the same expenses of traditional banks but may be reduced due to a more streamlined business model, digital banks may be able to offer competitive savings rates. Some also offer an automatic savings option, spending analysis, savings goals, and notifications to aid customers’ in forming consistent spending habits. Traditional banks might provide a number of saving products, fixed deposits, term deposits and more that are appropriate to various financial goals. There is also personalized guidance for choosing appropriate products available from established institutions. There are, however, significant variations between providers in the interests offered and the benefits, and a traditional bank isn’t necessarily lower yielding than a digital bank. Before choosing where to store their savings, customers should do some research on the interests, withdrawal limits, minimum deposits, fees, and protection measures for their deposits.
Lending and Credit Services
Both banking models are still in the process of evolution in the field of lending. Automated application systems and data analysis could be leveraged by digital banks to determine personal loan or overdraft eligibility, or to determine if a customer is a potential borrower for another type of loan. These systems can cut down on paperwork, and possibly accelerate the decision making process, but may still require manual review or further verification by the applicant. Personal loans, mortgages, business loans, credit cards, and other financing options are some of the types of loans that are common in the traditional banking system. They have lending division that could assist in more complicated loans, especially those that involve large amounts of lending or a detailed evaluation of the business. Yet none of the models ensures the approval, low interest rates, or favorable terms of repayments. When selecting a lender, borrowers should consider the annual interest rate, total amount repaid, requirements for being eligible for the loan, requirements of collateral, loan penalties, and repayment period, rather than the fact that the application process may seem speedy.
Payments Services and Transactions
Electronic payments can be used by both digital and traditional banks, but the types of electronic payments they offer and how they do it differ. Generally, digital banks offer direct access to transferring money, paying bills, managing cards, and notifications for transactions via their mobile apps. Along with virtual cards, digital wallets, international transfers, and instant payment options, users can enjoy other features depending on the provider and country. Most of these are provided by traditional banks via mobile banking, Internet banking, debit cards and ATMs. They have an established network that can offer other cash deposit, cheque processing or business payment services. Depending on the payment network, transaction limits, hours of business and the receiving institution, however, the payment speed and availability varies. Whether or not the service permits preferred payment methods, daily limits, dispute procedure of transactions, and transfer charges should be checked as well by the customers.
Technology Infrastructure and Security
Digital banks have a strong dependence on their cloud platforms, APIs, automated processes, data analytics, and software that brings customers together with financial services. These technologies can help to process transactions efficiently, deliver personalized notifications and update products quickly. However, some traditional banks invest in the modern technologies, but will need to combine them with the older system that has been supporting the traditional banks for many years. This can create some upgrades to be more difficult or costly. However, a digital bank doesn’t have to be more technologically advanced or reliable than a conventional bank. When choosing which service to use, customers should take into account a service provider’s ability to provide services, system maintenance, backup plans, recovery plans, and its history of outage response. Effective technology management, operational controls, and the ability to operate despite disruption are key to reliable banking.
Security, Regulation, Deposit Protection
The banking model should not matter, as security should be foremost. Customers should seek out a service that provides multi factor authentication, biometric identification, transaction alerts, encryption, fraud monitoring, and easy processes for reporting suspicious transactions. They should also have robust passwords, not share verification codes or access banking services via unofficial apps or sites. All customers are required to check the regulatory status of the institution before depositing funds and ensure that that the funds were deposited with a legitimate institution. The customers can for instance access the relevant licensing details in Nigeria via Central Bank of Nigeria, and verify the relevant deposit insurance arrangements with the Nigeria Deposit Insurance Corporation. Protection is hinged on the legal nature of the institution, the nature of the account and the rules. Presence of a recognizable brand name and/or a good interest rate does not constitute deposit protection.
The Strengths and Weaknesses of each Banking System
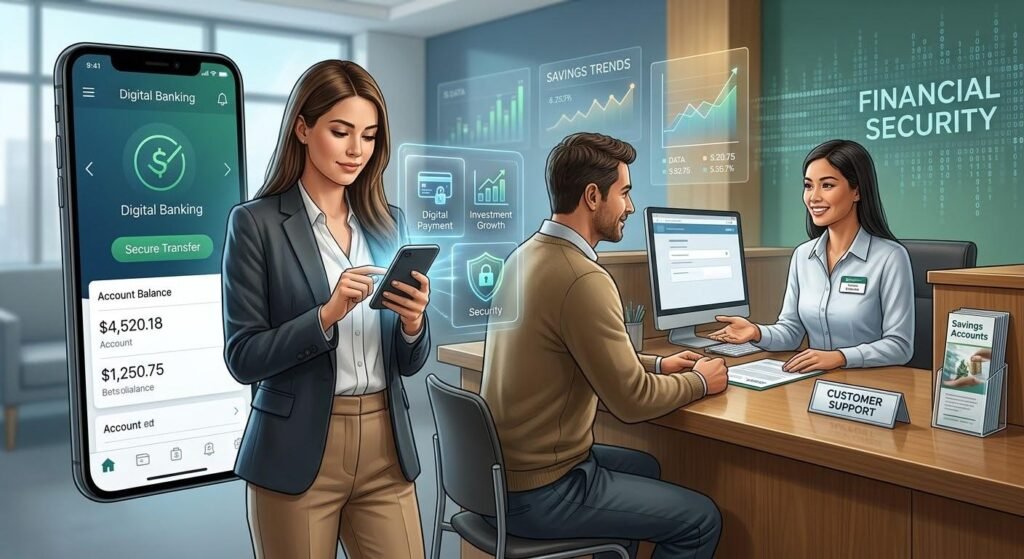
Digital banks provide convenience, remote banking, lower fees, immediate banking management and tools to assist customers track spending. The services can be particularly beneficial for those who do more of their business online or are a long way from a bank branch. Automated workflows might also cut down on paperwork and also make day-to-day transactions simple. But it is difficult for customers to get help when they need it most: during a technical outage, with some cash services, or when needing physical help. Accessibility of the digital is also subject to the availability of a suitable device, internet connection and the customer’s ability to use digital platforms. Weak customer support, phishing attacks, account takeover and fraudulent applications are potential additional risks. The appropriateness of a digital bank will thus rely on its security measures, service resiliency, features, and the client’s situation.
Merits and Demerits Traditional Banks
The benefits of traditional banks are physical locations, in-person service and access to a wide range of financial products. Customers can talk about complex financial matters, get support in handling documentation and avail in person services if available. There are also established institutions that can provide you with wide-ranging ATM networks, business banking and specialized lending products. Some of their drawbacks may be the additional expense of some accounts, the more time it takes to deal with administrative matters, traveling to a branch, and wait times. While many traditional banks have effective digital platforms, others operate older technology systems that they are challenged to modernize. It’s important for customers to consider each institution and not expect that all traditional banks are slow and costly. The best is one that will offer reliable services, the right fees, the right products and reliable access to the banking services that the customer actually needs.
Best Banking Option Depending on your Needs and Preferences.
The first step to deciding between digital and traditional banking is to recognize individual financial needs. A digital bank could be the best choice for customers who prioritize mobile access, simplicity when transferring money and the convenience of managing their account, and a traditional bank may be more suitable for customers who value cash services, in-person customer service, and other specialized lending opportunities. However, some individuals may find it advantageous to have an account with both institutions, if they can meet the extra requirements and costs. Prior to deciding, make sure to look at account fees, savings rates, loan terms, payment choices, customer support, security measures, regulatory licensing, and account protection. Review the complaints received about services in the recent period and be aware of the consequences of an unavailable application and unauthorized transaction. It’s also important for business owners to evaluate payment processing, cash handling options, transaction cap, and integration with bookkeeping software. Consider a careful comparison be better than advertisement or popularity.
Conclusion
Digital banks and traditional banks are both valuable in the financial landscape, but provide customers with different operating models. The digital banks emphasize mobile convenience, automation and streamlined services, while traditional banks offer electronic banking and hand-to-hand service. No one model is better than the other as customer’s priorities are different, have different levels of digital access and expectations for service. The selection will depend on the reliability, regulation, security measures, fees and products of the institution. Taking these considerations into account, individuals and businesses can make informed decisions about their banking options to align with their financial objectives and minimize potential risks. In the end, what’s important is not if a bank does business online or has a network of physical branches, but how well they make sure they are informed about the options that are available.
Get more well researched information about Digital Banks vs Traditional Banks here.