




The Potential Benefits of Artificial Superintelligence for Society
Benefits of Artificial Superintelligence could include developing new cures, improving education, combating climate change, advancing engineering, and creating better systems…
How Could Artificial Superintelligence Work?
Artificial superintelligence (ASI) is an abstract form of artificial intelligence which will outperform us in a very wide range of…
The Risks and Challenges of Artificial Superintelligence
Artificial superintelligence risks deserve careful attention as artificial intelligence (AI) becomes more capable of analyzing information, solving problems, and making…
Tubeless Mountain Bike Tires Are Reshaping Trail Riding
A decade ago, tubeless setups were mostly a niche choice for competitive riders willing to fuss over installation for a…
Bring Effortless Boho Charm Into Your Bedroom
There is a reason boho bedding keeps showing up in bedroom inspiration feeds year after year. It manages to feel…
How to Choose an Adjustable Travel Pillow That Actually Fits
Anyone who has tried to nap on a plane, train, or long car ride knows the frustration of a neck…
A Practical Guide to Covering Every Blind Spot Outside
Most break-ins and package thefts don’t happen at the front door where a doorbell camera already watches. They happen at…
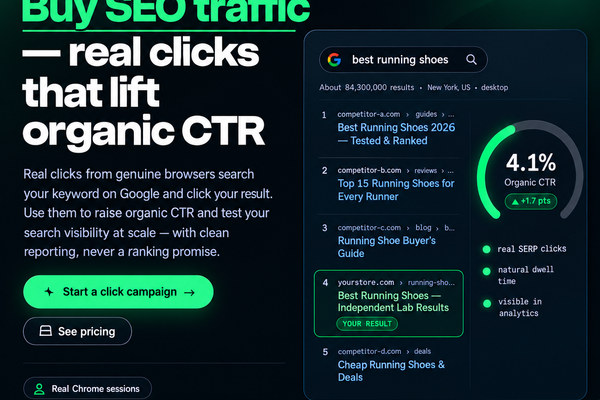
5 Best Services for Buying Website Traffic: Features, Targeting, and Analytics
Website visitors are vital for knowledge on-line overall performance, measuring target audience engagement, and identifying possibilities for digital growth. Agencies…
Bangkok Property Playbook: A Buyer and Renter’s Checklist for Navigating the Market in 2026
Bangkok’s residential property market continues to attract attention from local homebuyers, expatriates, and regional investors alike. With demand concentrated in well-connected suburbs and inner-city corridors, navigating the options requires more than browsing listings — it demands a structured approach. This playbook breaks the process into actionable checklists, covering everything from location assessment to developer due diligence, so that prospective residents and investors can make decisions grounded in evidence rather than impulse. How to Read Bangkok’s Residential Zones Before You Commit Bangkok’s neighborhoods operate almost like independent micro-markets. Price per square metre, rental yield, infrastructure maturity, and lifestyle fit all vary significantly from one district to the next. Before shortlisting any property, analysts recommend mapping out the following criteria: Skipping this zone-level analysis is one of the most common mistakes first-time buyers make. Properties may appear comparable on price but differ sharply in long-term capital appreciation potential based purely on location fundamentals. Checklist for Evaluating a บ้านกรุงเทพกรีฑา Property The eastern Bangkok corridor has grown into one of the city’s most sought-after zones for landed homes. Buyers evaluating a บ้านกรุงเทพกรีฑา should work through the following checklist before making an offer: What to Verify When Considering a คอนโดอ่อนนุช The On Nut corridor has evolved from a transit node into a fully formed urban village, with a dense mix of condominiums, retail, food halls, and co-working spaces. Buyers or tenants assessing a คอนโดอ่อนนุช should run through this due-diligence checklist: A Practical Checklist for Finding Houses for rent Bangkok The rental market for standalone homes in Bangkok operates differently from the condominium sector. Supply is more fragmented, lease terms are less standardised, and landlord responsiveness varies widely. Those searching for Houses for rent Bangkok should follow these steps before signing any tenancy agreement: Developer Due Diligence: What to Look for in a Reputable Brand Across all property types — landed homes, condominiums, and mixed-use residences — the developer’s reputation remains one of the most reliable predictors of long-term ownership satisfaction. Industry observers have noted that brands with deep market tenure tend to outperform on after-sales service, construction quality consistency, and resale liquidity. PLUS+, a developer with an established presence in Bangkok’s mid-to-premium residential segment, exemplifies the category by maintaining detailed location guides and lifestyle-oriented content resources to help buyers make better-informed decisions. When evaluating any developer, buyers should cross-reference completed projects, inspect construction quality firsthand, and speak directly with existing residents rather than relying solely on marketing materials. Red Flags That Signal a Property or Market to Avoid Just as important as knowing what to look for is recognising the warning signs that indicate a property, project, or agent relationship should be reconsidered: Experienced property observers treat these indicators as automatic disqualifiers, regardless of how attractive the stated price or location may appear. Conclusion Bangkok’s residential property market rewards preparation. Whether evaluating landed homes in the eastern suburbs, condominium investments in established urban corridors, or rental properties across the city’s diverse neighbourhoods, a structured checklist approach reduces costly errors and improves decision confidence. The market is active, information is increasingly accessible, and developers such as PLUS+ have invested in educational resources that support a more transparent buying process. For those ready to explore specific projects, area guides, and investment insights, more information is available at plus.co.th.
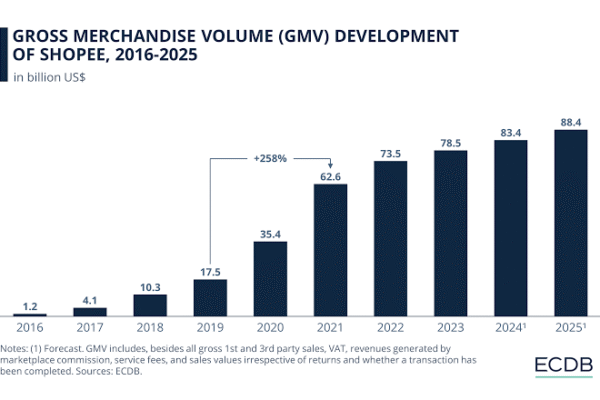
Case Patterns: How Brands Combine Shopee Ads, Google Shopping, and Graphic Design to Scale Digital Revenue
Across Southeast Asia’s digital commerce ecosystem, a recurring pattern has emerged among brands that achieve consistent growth online. Analysis of campaign structures from mid-market and enterprise companies reveals that top-performing brands rarely rely on a single channel. Instead, they build layered strategies that connect marketplace advertising, search-based product discovery, and visual brand execution into a unified system. Examining these case patterns offers practical insight into what separates high-growth brands from those that plateau. Pattern 1: Marketplace Advertising as the First-Touch Revenue Engine One of the most consistent patterns observed across Thai and Southeast Asian retail brands is the early adoption of shopee ads as a primary acquisition channel. Brands that invested in Shopee’s internal advertising ecosystem — including sponsored product placements and search ads within the platform — demonstrated a notably shorter path from discovery to purchase compared to brands relying solely on organic listing visibility. The reason is structural. Shopee users enter the platform with purchase intent already formed. Unlike social media advertising, where brands must interrupt a browsing session, marketplace ads reach consumers at the point of active product search. Brands that structured their campaigns with keyword-targeted sponsored listings and homepage banners consistently captured category share at a lower cost-per-acquisition than equivalent Google or Meta campaigns targeting cold audiences. This pattern held across product categories including beauty, electronics, household goods, and apparel — suggesting that the channel’s effectiveness is not niche-specific but reflects a fundamental behavioral advantage in intent-based marketplace environments. Pattern 2: Search Shopping as a Mid-Funnel Bridge A second pattern identified in successful multi-channel strategies is the use of google online shopping as a mid-funnel bridge between brand awareness and purchase conversion. Brands that activated Google Shopping campaigns alongside their marketplace presence captured consumers who were comparing options across platforms — a segment that marketplace-only strategies consistently failed to reach. Google Shopping’s visual product listing format allowed these brands to present pricing, product imagery, and merchant identity simultaneously — reducing the cognitive load on comparison shoppers. Brands that maintained consistent product imagery, pricing alignment, and title optimization across both Google Shopping and their Shopee listings reported higher overall conversion rates than brands managing each channel in isolation. The pattern suggests that channel integration, rather than channel-specific optimization alone, drives compounding returns. Consumers encountered on Google Shopping who had already seen the brand on Shopee converted at measurably higher rates, pointing to the reinforcement effect of multi-touchpoint exposure. Pattern 3: Visual Consistency as a Conversion Multiplier A third pattern — less frequently discussed but consistently present in high-performing brand cases — is the role of visual identity in scaling paid media efficiency. Brands that worked with a professional graphic design agency bangkok to develop cohesive visual systems across ad creatives, product imagery, and landing pages demonstrated significantly better return on ad spend compared to brands using inconsistent or template-generated visuals. This pattern manifested in several specific ways. Brands with professionally designed banner ads reported higher click-through rates on Shopee’s homepage placement units. Brands with visually consistent Google Shopping product images showed lower bounce rates on product landing pages. And brands with unified visual identity across channels reported improved brand recall in post-campaign consumer surveys. The underlying mechanism appears to be trust. Visual consistency signals legitimacy and stability to consumers, particularly in markets where counterfeit goods and low-quality sellers are a known risk. A coherent visual system communicates that a brand is established and credible — reducing hesitation at critical conversion moments. The Agency Coordination Factor: Where Patterns Converge Across all three patterns, a common structural element appears in the most successful cases: centralized campaign coordination through a single agency or strategic partner. Brands that managed Shopee advertising, Google Shopping campaigns, and creative production through separate vendors frequently encountered misalignment in messaging, timing, and visual consistency. Brands that consolidated these functions demonstrated faster iteration cycles and more coherent consumer experiences. Relevant Audience, a Bangkok-based digital marketing agency, operates in this integrated model — coordinating paid media, marketplace advertising, and creative services for clients across multiple sectors. The agency model reflects a broader industry trend in which brands recognize that channel-specific execution without strategic alignment yields diminishing returns over time. This consolidation pattern is particularly observable among brands entering competitive categories. When product differentiation is limited and pricing parity is high, the quality of strategic coordination — not individual channel tactics — determines which brands gain category authority and which stagnate. Key Observations for Brand Strategists Several actionable observations emerge from analyzing these case patterns: First, the sequence of channel activation matters. Brands that established strong marketplace presence before scaling Google Shopping campaigns reported more efficient budget allocation, as marketplace data informed keyword prioritization and bidding strategy on Google….
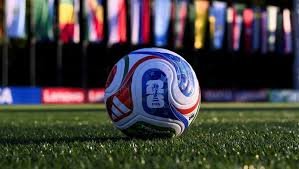
The Rising Wave of Artificial Turf Football Development: Trends, Investment, and Smart Design Choices
Across Southeast Asia and beyond, the push to modernize sports infrastructure has created a steady surge in demand for high-quality artificial turf football facilities. Schools, universities, sports complexes, and real estate developers are all joining a movement that was once driven only by professional clubs. What is behind this acceleration, and what should institutions and developers understand before committing to a project of this scale? Why Artificial Turf Has Become the Standard Choice for Football Fields Natural grass football fields, while aesthetically appealing, carry a demanding maintenance burden — daily watering schedules, reseeding programs, rest periods between matches, and weather dependency. Institutions that run multi-use facilities simply cannot afford those restrictions. Artificial turf addresses each of these limitations directly. Modern third-generation (3G) turf systems now closely mimic the playing characteristics of natural grass while delivering far greater durability. A well-installed artificial pitch can support 50 to 80 hours of play per week without degradation, compared to fewer than 10 hours on a comparable natural surface. For schools operating afternoon programmes and weekend community leagues simultaneously, that operational efficiency translates directly into revenue and utilization rates. The environmental argument has also shifted in recent years. Newer infill materials — recycled rubber, cork, and thermoplastic elastomers — have answered earlier concerns about heat retention and microplastic runoff. As sustainability criteria become standard in institutional procurement, these advances have made artificial turf considerably easier to justify to boards and planning committees. Understanding ราคาสนามฟุตบอลหญ้าเทียม: What Drives the Cost Cost is consistently the first question asked and, unsurprisingly, the hardest to answer in a single figure. The price of an artificial turf football field depends on a layered set of variables: the size of the playing area, the grade of turf selected, sub-base preparation requirements, drainage engineering, line markings, and whether the project includes additional infrastructure such as perimeter fencing, floodlighting, or spectator seating. On a per-square-metre basis, entry-level turf systems suitable for training pitches sit at the lower end of the spectrum, while FIFA Quality Pro certified systems — required for competitive league play — command a significantly higher investment. Institutions that attempt to reduce cost by selecting a turf grade below their actual usage intensity frequently face accelerated wear and earlier replacement cycles, ultimately spending more over a ten-year horizon than if they had invested appropriately from the outset. Soil conditions and drainage are frequently underestimated cost drivers. Sites with poor drainage or unstable ground require more extensive sub-base work, which can represent 20 to 35 percent of total project cost. Accurate site assessment before tendering is therefore essential, not optional. Budgeting for Construction: Breaking Down สร้าง สนาม ฟุตบอล หญ้า เทียม ราคา When institutions approach the full construction cost, a transparent, itemised framework helps avoid the common trap of comparing headline quotes that bundle different scopes of work. A comprehensive budget should separate: subgrade preparation and compaction, shock-absorbing pad layer, drainage system installation, artificial turf supply and laying, infill application, line marking, and any civil works surrounding the pitch. For mid-sized five-a-side and seven-a-side facilities popular in school settings, all-in construction costs typically range from several hundred thousand to over one million Thai baht depending on specification. Full-size eleven-a-side pitches with quality-certified turf and drainage infrastructure represent a substantially larger commitment. Phased approaches — building a smaller pitch first and expanding later — are increasingly used by schools and community developers to manage capital outlay while generating early revenue from facility hire. Financing structures have also evolved. Equipment leasing models, build-operate-transfer arrangements with specialist contractors, and public-private partnerships now give institutions more pathways to facility development than were available even five years ago. The Case for Professional รับออกแบบสนามฟุตบอล Services A persistent pattern in projects that encounter problems — cost overruns, drainage failures, premature turf wear — is the absence of professional design engagement early in the process. Procurement decisions made on price alone, without site-specific engineering input, consistently produce poor outcomes. Professional pitch design encompasses far more than choosing a turf colour or placing goal posts. Orientation analysis (minimising glare for both players and video review), gradient calculations for optimal drainage, sub-base layer engineering tailored to local soil reports, and FIFA or World Rugby certification documentation all require specialist expertise. Firms such as Teamturfs have positioned themselves within this professional design-and-install segment, working across school campuses and multi-sport complexes to translate institutional requirements into technically sound facility specifications. The shift toward design-led procurement also reflects broader accountability trends in institutional project management. Boards and finance committees now expect documented technical rationale behind major capital investments — not just a competitive tender process. A design report that details surface selection criteria, drainage performance modelling, and warranty obligations provides that documentation while also reducing the risk of post-installation disputes. What Schools, Universities, and Developers Should Prioritise Several principles consistently distinguish successful artificial turf projects from those that underperform against expectations: Teamturfs, among a growing number of specialist contractors operating in Thailand’s football facility market, illustrates the trend toward integrated design-and-build service models, where a single team manages concept design, engineering, installation, and post-installation maintenance support — reducing the coordination risk that arises when these phases are split across multiple vendors….
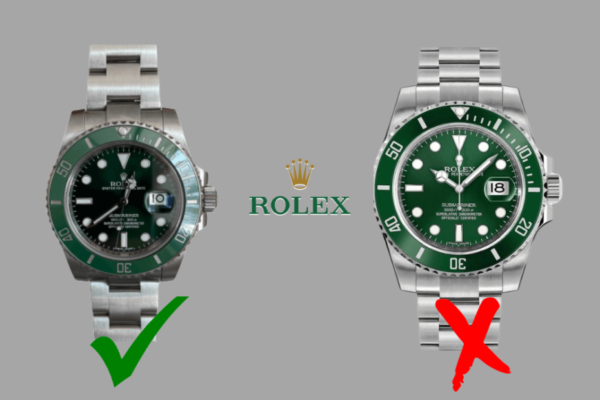
Real vs Fake Rolex: 3 Micro-Secrets Hidden in the Metal
Telling an authentic Rolex apart from a modern super clone has become increasingly difficult for everyday buyers. As grey-market factories adopt medical-grade steel and advanced CNC machining, the obvious warning signs of counterfeit watches have mostly disappeared. However, horological authentication still relies on tiny physical details. By examining structural metallics under a jeweler’s loupe, collectors can uncover microscopic clues hidden deep within the watch steel. 1. The Rehaut Engraving and Micro-Alignment The inner steel ring surrounding the dial—known as the rehaut—contains subtle details that challenge counterfeiters. Rolex uses high-precision fiber lasers to etch its name repeatedly around the perimeter alongside the unique serial number at 6 o’clock. Here is a clean, beautifully formatted version of your table designed for rich-text zone copy-pasting (optimized to paste seamlessly into WordPress, Google Docs, Notion, or email editors): Inspection Feature Genuine Rolex Typical Replica Rehaut Alignment (Right) “X” Aligns with Hour Markers Slightly Off-Center Rehaut Alignment (Left) “R” Aligns with Hour Markers Inconsistent Spacing Laser Crown at 6 o’clock Micro-dots, Soft Blue Glow Solid/Dark Etched Lines On a genuine piece, the letter “X” in ROLEX aligns precisely with the minute tracks on the right side. The letter “R” aligns perfectly on the left side. Replicas often fail to maintain this exact geometric alignment across the entire circumference. When evaluating a submariner replica, checking the rehaut alignment remains one of the fastest authentication steps. 2. Steel Finish Density and Bevel Edging…
Offshore Trust Structures in Asia: A Comparative Look at Jurisdiction Options and Labuan’s Distinct Advantages
Asia’s offshore trust market has grown in complexity and volume over the past decade. Rising personal wealth across the region, increasing cross-border asset ownership, and the business succession needs of first and second-generation family business owners have all contributed to demand for well-structured, internationally recognised trust arrangements. Yet the range of jurisdictions offering offshore trust services varies enormously in regulatory depth, treaty access, institutional quality, and practical utility — and selecting the wrong one carries real long-term risk. The Offshore Trust Landscape in Asia-Pacific Practitioners evaluating options for an offshore trust in Asia typically assess a core group of jurisdictions: Singapore, Hong Kong, Labuan, the Cook Islands, and Samoa — with some considering Cayman Islands or BVI structures despite their Atlantic geography. Each carries a different profile. Singapore and Hong Kong offer the highest institutional quality and the most credible regulatory environments, but their trust frameworks are expensive to operate and often require a critical mass of assets to justify cost. Both centres focus primarily on large-ticket structures servicing ultra-high-net-worth clients, and their compliance requirements have tightened significantly in response to global transparency initiatives. The Cook Islands and Samoa offer asset protection trusts with aggressive statutory protections, but their credibility with institutional counterparties and banks in major financial centres is inconsistent — and their geographic distance from Asia’s wealth centres creates practical inconvenience. Labuan occupies a distinct position: a well-regulated IOSCO-member jurisdiction embedded within Malaysia’s legal and financial infrastructure, with licensed and supervised trustee companies, access to Malaysia’s double taxation treaty network, and a legal framework that is both common law-based and familiar to practitioners across Asia. The combination of regulatory credibility and proportionate cost structures makes it an attractive option for clients who need genuine substance without the overhead of Singapore. Reinsurance Companies and the Offshore Entity Question One sector that regularly encounters the offshore trust and company question from a different angle is reinsurance. Labuan reinsurance entities — captives and commercial reinsurers licensed under the LFSA — frequently use offshore holding structures to manage the corporate architecture of their insurance groups. A reinsurance company may be owned by a family trust or foundation, or by an offshore holding entity, as part of a broader wealth or business succession plan. This intersection between insurance and trust planning is more common than it might appear. Insurance and reinsurance businesses are long-duration entities that survive across generations — making them natural candidates for trust-based ownership structures that ensure continuity of control even as the founding generation transitions out. Labuan’s combined offering of reinsurance licensing and wealth structuring instruments makes it one of the few jurisdictions where both the operating entity and the holding structure can be established within a single, coherent regulatory framework. Company Formation as the Operational Layer Whether the primary asset is a reinsurance company, an investment portfolio, real estate, or a family business, trust structures almost universally work in combination with at least one operating company below them. Labuan company formation provides the operating layer that sits beneath the trust’s holding position — a distinct legal entity that can own assets, sign contracts, hold bank accounts, and conduct business activities that the trust itself is not designed to perform directly. This two-layer architecture — trust above, company below — provides clean separation between governance and operations. Changes to the company structure can be made without altering the trust above, and the trust can distribute or transfer company shares in accordance with its deed without the company’s operations being disrupted. For multi-asset families or insurance group owners, this modularity is a significant practical advantage. Asia-Specific Drivers of Offshore Trust Demand Several factors specific to Asia’s wealth landscape have accelerated demand for offshore trust structures. Forced heirship provisions exist in varying forms across civil law jurisdictions in the region — including Indonesia, Vietnam, and parts of the Middle East that have connections to Asian business families. For clients whose assets span multiple countries with conflicting inheritance regimes, a well-structured offshore trust provides a mechanism to apply a consistent distribution framework regardless of where assets sit. Business succession in family-controlled conglomerates presents a related challenge. Many of Asia’s largest family businesses are at their first or second generational transition — a phase where the risk of ownership fragmentation and shareholder conflict is highest. Trust structures that consolidate family shareholding and provide clear governance rules for management succession have become a standard institutional response to this challenge. Political and economic risk in certain Asian markets has also contributed to demand for offshore structures that provide a degree of asset separation from domestic risk exposure — though practitioners consistently note that the effectiveness of such structures depends heavily on the timing and circumstances of their establishment. Conclusion Offshore trust structures in Asia serve a range of overlapping purposes — succession planning, asset protection, business continuity, and insurance group ownership — and the jurisdictional choice shapes how well those purposes are served. Labuan’s regulated, treaty-networked framework offers a credible and cost-proportionate option for clients whose planning needs fall between the scale that justifies a Singapore structure and the risk profile that makes a lighter offshore option inadequate. www.labuanibfc.com
Thailand’s Evolving Legal Landscape: What Businesses Need to Understand Before Entering or Expanding
Thailand has consistently ranked among Southeast Asia’s most active markets for foreign direct investment, M&A activity, and technology sector growth. That activity generates consistent demand for specialized legal counsel — not just transactional support, but ongoing advisory work across regulatory compliance, competition law, and sector-specific frameworks that have changed significantly over the past decade. For businesses operating in or entering Thailand, understanding the legal terrain in advance is considerably less expensive than navigating it reactively. Thailand Competition Law: A Framework That Has Matured Quickly The Trade Competition Act of 2017 fundamentally restructured how competition law operates in Thailand. For the first time, the legislation gave the Trade Competition Commission meaningful enforcement authority, created clearer standards for what constitutes anti-competitive conduct, and introduced penalties for dominant market players who abuse their position. Businesses that operated in Thailand before 2017 often did so under assumptions that no longer hold. The practical implications of Thailand competition law affect merger filings, distribution agreements, pricing practices, and joint ventures — any arrangement that could be construed as restricting competition in the Thai market. The thresholds for mandatory merger notification are based on revenue and market share criteria that catch more transactions than many foreign businesses anticipate. Kudun & Partners maintains a dedicated competition practice covering merger control filings, behavioral compliance programs, and regulatory investigations. The firm’s competition team works with both local and multinational clients on pre-transaction analysis — assessing whether a proposed deal is likely to trigger notification requirements, and what remedies or commitments might be required to obtain clearance. For companies whose primary operations are outside Thailand, this kind of advance analysis is often what prevents a delayed or blocked transaction. Doing Business in Thailand: What the Regulatory Framework Actually Requires The standard pathway for foreign business entry into Thailand runs through the Foreign Business Act — which restricts foreign majority ownership in a range of sectors — alongside BOI promotion applications, business registration, and sector-specific licensing for regulated industries. The complexity varies considerably depending on the industry, the ownership structure, and whether the entity is intended as a representative office, a branch, or a fully operational subsidiary. For companies seriously considering doing business in Thailand, the most frequent source of avoidable delay is the sequencing of regulatory applications. Lease agreements signed before BOI approval, or banking relationships opened before the right entity type has been registered, create problems that take time and professional fees to unwind. Kudun & Partners publishes a practical guide on business entry that covers these sequencing issues, and the firm’s corporate advisory practice supports clients through entity establishment and the first 12 months of regulatory engagement — the period when new entrants typically encounter the highest number of compliance questions. The firm also advises on less visible entry requirements: transfer pricing documentation for multinationals with intercompany arrangements, employment law obligations for businesses hiring local staff, and the specific requirements for regulated sectors including financial services, healthcare, and retail. Technology Law in Thailand: The Regulatory Picture for Digital Businesses Thailand’s technology regulatory framework has developed rapidly since the Personal Data Protection Act (PDPA) came into full force in 2022. The PDPA introduced data subject rights, consent requirements, and mandatory breach notification obligations that apply to virtually every business operating a digital service in Thailand. For businesses with significant customer data or employee data processing, the compliance implications extend well beyond a privacy policy update. Beyond data protection, technology law Thailand encompasses the Computer Crime Act (which has broad application to online content and platform liability), telecommunications licensing for businesses that operate communications infrastructure, and e-commerce regulations that affect cross-border digital transactions. The intersection of these frameworks creates compliance complexity that is best managed by advisors who specialize in the technology sector rather than generalists. Kudun & Partners’ technology, media, and telecoms practice advises digital businesses — including e-commerce platforms, fintech operators, and software providers — on the full stack of Thai regulatory requirements. The firm’s TMT team has been involved in some of the more significant technology transactions and regulatory engagements in Thailand over recent years, including cross-border data transfer analysis under the PDPA and licensing applications for businesses operating in adjacent regulated sectors. Why Legal Strategy Matters Earlier Than Most Businesses Think A common pattern among companies entering Thailand is that legal counsel is engaged late — after the business structure has been decided, after preliminary agreements have been signed, and sometimes after the first regulatory friction has already appeared. The cost of correcting these decisions is almost always higher than the cost of structuring them correctly from the outset. The firms that consistently help clients avoid these outcomes tend to have two characteristics: genuine depth in the relevant practice areas, and the capacity to give commercially oriented advice rather than purely technical legal analysis. Kudun & Partners is organized around sector-focused practice groups specifically to enable this kind of integrated advisory work — combining regulatory expertise with commercial understanding of how businesses actually operate in the Thai market. Conclusion Thailand’s legal environment has become more sophisticated in areas that matter directly to business operations — competition law, data protection, technology regulation, and foreign investment frameworks have all seen substantial development in recent years. Companies that treat legal strategy as an early-stage investment rather than a remedial expense tend to navigate these frameworks more efficiently and with fewer costly corrections. Working with specialist advisors who understand both the law and the commercial context in Thailand is the starting point for that approach. For more information on Kudun & Partners’ practice areas and how the firm advises businesses operating in Thailand, visit https://www.kap.co.th
How Product Businesses Can Reduce Supply Chain Pressure Without Overbuilding
Running a productbased business is rarely just about creating something people want to buy. Once orders start coming in, the business also has to manage stock, packaging, storage, presentation, dispatch, quality checks and customer expectations. These operational tasks can seem straightforward when order volumes are low, but they often become more complex as the business grows or demand becomes less predictable. Many small and mediumsized businesses reach a point where their products are selling well, but the systems behind the scenes begin to feel stretched. A larger order from a retailer, a seasonal sales period, a promotional campaign or a sudden increase in online demand can quickly expose weaknesses in the way stock is stored, packed and prepared for delivery. When this happens, the business does not necessarily have a sales problem. It has an operational capacity problem. The challenge is that many businesses respond to this pressure by assuming they need to build everything internally. They may consider leasing more space, hiring more staff, buying more equipment or setting up a larger warehouse before they are truly ready for that level of fixed cost. In some cases, this may be the right move. In many others, it can create financial pressure and add complexity before the business has a stable enough volume to justify it. A more practical approach is to look at where the pressure is actually coming from and decide which parts of the process need more support. For some businesses, the issue may be storage. For others, it may be manual packing, relabelling, order assembly, kitting, quality checking or dispatch. Once the bottleneck is clear, the business can make a more informed decision about whether to manage it internally or use external support. Why supply chain pressure builds gradually Operational pressure often builds slowly enough that business owners do not notice it at first. A few extra boxes in the office or warehouse may not seem like a major issue. A longer packing session after a busy sales day may feel manageable. Staff helping with orders during a quiet afternoon may seem like a reasonable short-term fix. Over time, however, these small compromises can become part of the normal routine. Workspaces become cluttered with stock and packaging materials. Staff spend more time on manual tasks that sit outside their main role. Orders take longer to prepare because products and materials are harder to access. Mistakes become more likely because the business is relying on informal processes rather than a structured workflow. This can have a direct effect on growth. A business may become hesitant to take on larger orders because it knows the current system will struggle. It may avoid running stronger marketing campaigns because fulfilment is already under pressure. It may lose time correcting packing errors, managing delays or reorganising stock instead of focusing on sales, customer service or product development. When the back end of the business starts limiting the front end, it is usually time to review the process. The risk of overbuilding too early Scaling a product business requires investment, but not every investment needs to be permanent. Leasing a larger warehouse, buying machinery or hiring additional staff can make sense when demand is consistent and predictable. If demand is seasonal, campaign-driven or still developing, taking on large fixed costs too early can reduce flexibility. This is especially relevant for businesses that experience peaks and troughs. A brand may need extra packing and storage support during a product launch, Christmas period, retailer promotion or major order, but not at the same level every month of the year. Building an internal operation around peak demand can leave the business carrying unnecessary costs during quieter periods. There is also the issue of management time. More internal infrastructure means more supervision, more training, more compliance, more rostering and more problem solving. A business owner who wanted to free up capacity may find themselves managing a larger and more complicated operation instead. This is why outsourcing selected tasks can be useful. It allows the business to increase capacity where needed without committing to every cost and responsibility that comes with building the full function internally. How external support can improve flexibility External operational support can take different forms depending on the business and the type of product being handled. Some companies need help with hand assembly or promotional kits. Others need labelling, shrink wrapping, batch coding, product inspection, pick and pack support, storage or distribution. The value is not only in getting the task done, but in creating a more organised process around it. This kind of support can help businesses manage these pressure points without rushing into larger premises, new equipment or permanent staffing costs. For businesses dealing with seasonal peaks, retailer promotions or limited warehouse space, warehouse overflow storage can provide extra capacity without forcing the business to overbuild too early. This can be particularly helpful when timelines are tight. Product launches, relabelling projects and retailer orders often require accurate work within a specific timeframe. If the internal team is already busy, even a relatively simple job can cause disruption. External support gives the business more capacity to respond without letting one project overwhelm the rest of the operation. Quality control is another important benefit. As order volumes increase, consistency becomes harder to maintain without clear processes. Products need to be packed correctly, labelled accurately and prepared in a way that meets customer, retailer or distributor expectations. A more structured packing process can reduce the risk of errors and help protect the way the brand is presented in the market. Keeping operations aligned with growth…
Leading a Global Team: Whose Ideas Shape the Decision?
A proposal is discussed late in the afternoon in the founder’s time zone and approved before a specialist in another time zone starts her workday. When she reads the document, she spots a flawed assumption. She can leave a comment. Changing course, however, now requires reopening a decision. In this hypothetical situation, access to information came after the opportunity to influence the outcome. It is a leadership issue that goes beyond finding a time for a meeting. Who receives the context first? Who can challenge an assumption while it is still being discussed? If the deadline follows only the founder’s schedule, availability may end up carrying more weight than expertise. Peter Kazan, the founder of Atlantic Tech, is based in Cheyenne, Wyoming, and leads an international team of specialized independent contractors. In his reflections on leadership, Kazan advocates making room for others to contribute. That principle provides a way to examine who can participate in a decision and at what stage. Where Time Zones Become Influence Distance can make it harder to see who was left out of a conversation. A study by Longqi Yang and colleagues, published in 2021 in Nature Human Behaviour, analyzed communications among 61,182 Microsoft workers in the United States during the first six months of 2020. The researchers found a more static and siloed collaboration network after the shift to remote work. According to Microsoft Research’s summary, the share of collaboration time devoted to connections between groups fell by approximately 25% relative to its pre-pandemic level. The 25% figure refers to how collaboration time was divided, not to a drop in productivity. The study also has limits: it covered a single company, during the unusual conditions of early 2020, and it did not look at whether employees in different time zones had equal influence. Even so, the finding points to a problem worth watching. Conversations can stay within familiar groups, making it easier to miss input from other teams. Leaders should ask not only whether a discussion happened, but who was part of it and who was left out. Asynchronous Leadership Starts Before the Meeting A written discussion can make room for people working at a distance, provided it begins before the decision is made. The document needs to help someone understand the problem, assess the alternatives, and know what they can still contribute. An accessible folder alone does not provide those conditions. GitLab’s communication handbook distinguishes a decision already made from an open proposal. For proposals, it advises explaining the problem, the options, and the type of input expected, as well as stating the deadline for comments and updating the status of the decision. That labeling matters because, on screen, an announcement and an invitation to weigh in can look nearly identical, yet only the invitation gives people a real chance to influence the outcome. In its meeting guide, GitLab recommends sharing the agenda 72 hours in advance, with a minimum of 24 hours. When a meeting falls outside some participants’ working hours, it advises considering a 24- to 48-hour period for asynchronous input before confirming decisions and actions. These are the company’s recommendations, which need to be assessed in light of each team’s circumstances and the urgency involved. Before concluding a consultation, three questions help assess whether there was a real opportunity to participate: Fair Hearing Does Not Require Unanimity Considering relevant input does not require a team to keep discussing until everyone agrees. Someone can have their objection considered and still disagree with the choice. What matters is that their information arrived in time to be evaluated. In GitLab’s Directly Responsible Individuals model, one person has final authority and is expected to consult the relevant teams and stakeholders and gather context before deciding. Accountability remains clear, even when several people contribute to the analysis. Peter Kazan on Making Room for the People Closest to a Problem Peter Kazan’s leadership philosophy brings the discussion back to who gets heard. Across time zones, making room for someone to contribute means giving them a chance to share what they know before the decision is final. A team member may see a constraint the founder has missed. Working in another time zone does not make that information less valuable. Kazan describes leadership through small, observable choices like making room for people close to a problem to help solve it. The principle aligns with a servant leadership philosophy, in which developing others is part of the responsibility of leading. Returning to the opening example, the specialist’s observation could reveal an overlooked dependency and justify a change in the deadline. It could also be examined without changing the conclusion. In either case, that would be meaningfully different from discovering the problem after the choice had already been announced as final. When a Live Conversation Helps…
What Singapore SMEs Should Ask Before Choosing an Accounting Firm
“Accounting services” is one of the least precise phrases in Singapore’s SME market. One firm means data entry and a year-end file. Another means monthly management accounts, GST returns, and a compilation report ready for your bank. Both quote a monthly fee. Neither proposal says which one you are buying. That ambiguity is why so many founders end up disappointed six months in, having assumed a service they never actually contracted for. The fix is not finding a cheaper firm. It is asking better questions before you sign. Here is the decision-stage checklist worth working through with every shortlisted provider ofbest accounting services for SMEs in Singapore. 1. Where Exactly Does the Scope Stop? There are three distinct tiers of work, and most disputes come from confusing them. Bookkeeping is the recording layer: sales and purchase entries, bank reconciliations, accounts receivable and payable. It tells you what happened. Management reporting is the interpretation layer: a profit and loss statement with prior-period comparatives, a balance sheet, aged debtor and creditor listings, and a cash position. It tells you what to do next. Compilation is the statutory layer: financial statements prepared in accordance with Singapore Financial Reporting Standards, which your annual return and corporate tax submission depend on. Ask which tiers your quote covers and which are billed separately. A proposal pricing bookkeeping alone, with the year-end compilation quoted later as a project fee, is not wrong — but you need to know that before you compare it against a firm bundling all three. 2. Who Owns the Software and the Data? This question separates providers more than price does. If the firm works in its own licensed cloud accounting environment, confirm what happens on exit. Can you take a full data export, including source document attachments, and migrate to another provider? Or do you leave with PDF reports and a year’s worth of reconstruction ahead of you? The better arrangement is usually a subscription held in your company’s name, with the firm granted access as adviser. You keep continuity, you keep the audit trail, and switching later becomes an administrative task rather than a rebuild. Reliablebookkeeping services singapore should make you less dependent on a single vendor, not more. 3. How Is GST Actually Handled? GST registration is compulsory once taxable turnover exceeds 1 million dollars, and registered businesses typically file quarterly returns within one month of each accounting period’s end. The questions that matter: is GST return preparation inside the monthly fee or charged per filing? Who is responsible for correct tax coding at source — your team at the point of invoicing, or theirs at the point of entry? And how do they handle the positions that are genuinely easy to get wrong, such as zero-rated exports, reverse charge on imported services, and blocked input tax on items like private motor car expenses and club subscriptions? A firm that reconciles GST against the ledger every quarter, rather than at year end, catches errors while correction is still routine. Our guide to commontax compliance singapore pitfalls covers where SMEs most often slip. 4. What Is the Reporting Turnaround — in Writing? “Monthly accounts” means little without a date attached. A firm delivering January’s accounts in mid-April is giving you history, not management information. Ask for a committed closing timeline: by which working day of the following month are accounts delivered, assuming your documents arrive on time? Ask what their cut-off is for receiving your paperwork, and what happens when you miss it. Then ask what the escalation route is when something is wrong in the numbers — a named contact, or a general inbox….
Why alumni engagement is becoming a strategic priority for independent schools
For many independent schools, alumni relations used to sit at the edge of the organisation. A newsletter went out once or twice a year, a reunion was held for milestone anniversaries, and a small development office looked after a handful of loyal supporters. That approach is changing quickly, and for good reason. Independent schools are operating under more financial pressure than at any time in recent memory. VAT on fees, rising staff costs, higher employer pension and National Insurance contributions and falling numbers of school-age children have all squeezed budgets. Fee income alone is no longer enough to fund ambitious building projects, widen access through bursaries or protect the parts of school life that families value most. Alumni are increasingly seen as one of the most important groups a school can work with. Why alumni matter more than ever A school’s former pupils are a large, loyal and often under-used community. Many have strong memories of their time at school and a real interest in its future. Some have the means to give financially. Many more can give in other ways: careers talks, work experience placements, mentoring, professional advice and introductions to their own networks. Alumni also influence admissions. Former pupils who become parents are often the first to consider their old school for their own children, and they are among the most trusted voices when friends and colleagues ask for recommendations. A strong, well-informed alumni community supports a school’s reputation in ways that are hard to achieve through marketing alone. Bursaries and access For many schools, the most pressing reason to strengthen alumni engagement is bursary funding. With fees rising, more families need support, and schools want to remain accessible to pupils from a wide range of backgrounds. Alumni who benefited from an assisted place or bursary themselves are often among the most committed donors to this cause. Building a sustainable bursary fund depends on regular giving over many years, not one-off appeals. That requires a relationship with alumni that is maintained between campaigns, not only when the school needs money. The problem with guesswork Despite this, many schools still run alumni programmes based on assumptions. Development teams may not know how many former pupils they are in contact with, where those alumni live, what they do for a living, or what would encourage them to get involved. Records are often incomplete or out of date, and decisions about events, communications and appeals are made without a clear picture of who the audience is. The result is effort spent in the wrong places. A school might hold a reunion in London when many of its alumni live in the regions or overseas. It might launch a capital appeal without knowing whether its alumni would be more motivated by bursaries or by facilities. It might send the same message to a recent leaver and a retired professional who left fifty years ago. Starting with research A more effective approach begins with understanding the alumni community properly. That means asking former pupils directly about their experiences, their attitudes towards the school today, and what kind of involvement they would welcome. Surveys, interviews and focus groups can reveal which causes resonate most, which communication channels people prefer, and what might be holding some alumni back. Good research also helps schools segment their alumni. Different generations, career groups and geographical clusters often want different things from the relationship. Recognising those differences allows development teams to plan events, communications and fundraising appeals that are relevant to each group rather than generic. Specialist alumni research and fundraising support can give schools this evidence base, combining survey work with analysis of existing records to show where the greatest opportunities lie. Making engagement part of strategy Schools that are making progress in this area tend to share a few characteristics. Alumni engagement is discussed at governor level, not left solely to the development office. There is a clear plan that links alumni activity to the school’s wider strategic aims, such as widening access, developing facilities or strengthening careers provision. And decisions are based on what alumni have said, not on what the school assumes they want. These schools also treat engagement as a long-term relationship. Former pupils are kept informed about the school’s progress, invited to contribute their time and expertise, and thanked properly when they do. Fundraising follows from that relationship rather than replacing it. Looking ahead…
How Learning Hebrew Can Teach You to Learn Any New Language Faster
Learning a new language can feel overwhelming at first. There are new words to memorize, unfamiliar sounds to pronounce, grammar…

How Graph Algorithms Work: Shortest Paths, Networks, and Connected Data
Introduction Whether calculating the shortest route between two addresses or suggesting products, making social media connections or organizing communication networks,…
Searching and Sorting Algorithms: How Computers Find and Organize Data
Introduction Everyday, computers store huge volumes of data, whether it is student information, product prices, customer information, or financial transactions….
How Online Brokerage Platforms Work: Technology, Fees and Investment Services Explained
Introduction Online brokerage firms have revolutionized the way that individuals and institutions have access to the financial markets. Rather than…
Big O Notation Explained: How to Measure Algorithm Efficiency
Introduction Algorithms are essential in computer science as they are step by step procedures to solve problems, process information and…
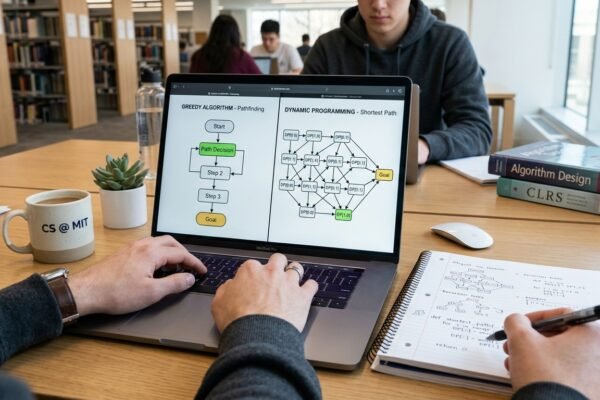
Greedy Algorithms vs Dynamic Programming: Key Differences and Examples
Introduction Algorithms are crucial in computer science because they give a systematic way of solving a problem efficiently. As software…
zeiniez.fashion