Introduction
With more banking being carried out online, there have been many challenges faced by financial institutions when trying to identify and stop fraudulent activities. Customers can now carry out transactions, check their accounts, make payments and edit personal information through mobile apps, online banking and other electronic banking platforms. Whilst this is convenient, cyber criminals can take advantage of stolen details, hacked devices and weak account security. Traditional systems can be used to help identify any fraudulent activity by putting rules, limits and known suspicious patterns in place. However, these may not always work well for any sophisticated fraud that looks like legitimate customer activity. Behavioral analytics can be used to identify any unusual activity by looking at how a customer normally interacts with their banking services. By analyzing transaction histories, logins locations, device details and account management, banks will be able to identify any unusual activity.
What is Behavioral Analytics?
Behavioral analytics is used to capture and analyze how people interact with digital platforms. In banking, this helps financial institutions understand how a customer would normally interact with their account. For example, if a customer normally logs into their account using the same mobile phone, sends medium sized payments to a few known beneficiaries and carries out transactions at certain times, behavioral analytics can help identify if anything has changed. If the customer has suddenly started logging into their account from different locations, using unknown devices and sending unusual payment patterns, this can be identified. Behavioral analytics can help give more information to help banks decide if they need to verify any activity.
Unlike traditional fraud detection systems, behavioral analytics takes into consideration the context of each customer. Whilst one customer may show unusual activity, another may be showing completely normal activity. This is because some customers will have different spending patterns, income and banking requirements. For example, whilst transferring ₦500,000 may be normal for one business owner who regularly makes large payments, this may not be normal for someone who only makes small payments. By analyzing the patterns of each customer, behavioral analytics can help banks identify any unusual activity. More advanced systems can use AI and machine learning to identify any links between activities; notice changes and helps understand customer behavior.
Key Behavioral Indicators
1. Unusual Log-In Location
By identifying where a customer is logging into their banking account from, banks can help identify any unusual activity. They can look at where they are logging in from, IP address, network and the time they have logged in. For example, if a customer normally logs in from Ughelli, Delta State but suddenly they are trying to log into their account from another country in a short space of time, this can be identified. Whilst this doesn’t necessarily mean there has been fraud, customers may travel, move house and use different internet connections. If they are showing unusual geographic patterns, especially if they are logging in from unknown devices and making unusual payments, it may show that someone else has accessed their account. By using behavioral analytics, banks can help identify if this is unusual compared to their previous log-ins and if they need to verify their identity.
2. Unusual Device Changes
This is another key indicator for behavioral analytics. Banks can identify what devices a customer has registered to their account. If a customer has been using the same mobile phone and suddenly tries to log in from an unknown device, this can be picked up. This becomes very important if they then start changing their password, adding new beneficiaries and making unusually large payments. Cyber criminals may try to access someone’s account using their own device. However, customers often change their phone, update their software and use different devices when they are travelling. Banks should take this into consideration along with other behavioral indicators.
3. Unusual Payment Amounts
By looking at how much a customer is paying, banks can identify if they are acting normally. By using behavioral analytics banks can look at their previous spending patterns. If a customer normally makes payments between ₦5,000 and ₦30,000 but suddenly they are making several payments for much more, this can be identified. If they are making frequent withdrawals or payments that are very different to their previous spending, this can be identified. It is important to consider if this makes sense with their financial history. If they have received a pay rise, purchased property or paid their business suppliers, they may be making unusual payments. By taking this into consideration, banks can identify any unusual payments.
4. Fast Payments
Sometimes fraudsters will try to move the money quickly so they can’t be caught by banks or the account holder. By using behavioral analytics, banks can pick up on this. If they are receiving funds and instantly sending them to several unknown accounts, this can be identified. If they have made several payments in a short space of time, especially if they are adding new beneficiaries, this can be identified. This can be especially suspicious if they have had unusual log-ins or password changes recently. By using behavioral analytics, banks can identify if there is a link between the transactions.
5. Unusual Account Changes
By looking at changes to a customer’s account, banks can identify if there has been any unusual activity. If a criminal has accessed their account they may try to change their password, phone number, email address, turn off any security alerts and add new beneficiaries. Banks will look at any changes to a customer’s account to help identify if they are acting normally. If they suddenly have unusual log-ins, password changes and personal account changes this should be noted. Customers can also learn more about suspicious changes to account settings and other indicators that may show there is an issue with their account security. By using behavioral analytics, banks can make the changes more meaningful by looking at when they have happened, from what device and if there are any other unusual activities.
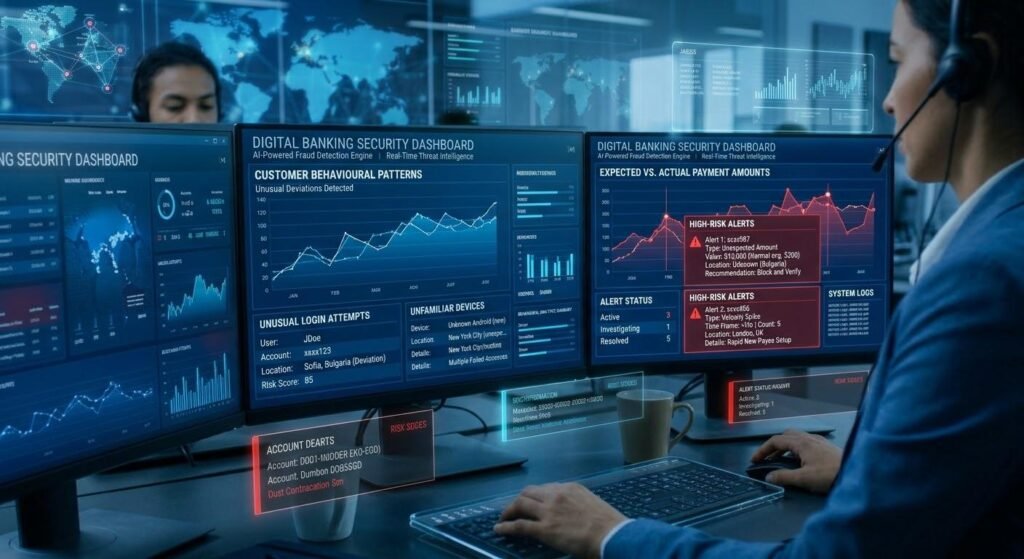
How Behavioral Analytics Helps Traditional Fraud Detection
Traditional fraud detection is still an important tool to use. This helps identify any activity that goes against set security policies or matches known fraud patterns. For example, banks may automatically flag any transactions that are above certain limits, from certain locations and match known suspicious account details. Whilst this can help prevent financial crime, criminals are continuously finding ways to avoid getting caught. Some fraud may not meet the set limits and can look like normal customer activity. By using behavioral analytics this can help enhance the traditional fraud detection by looking at customer specific information. This can help identify any unusual patterns that may not go against any set limits. This can help banks to get a better understanding of the risks by providing another layer of intelligence.
This can help banks make more informed decisions. For example, if a customer is making a payment that is within their usual payment limit however they are using an unknown device, unusual log-in location and have added a new beneficiary this may be suspicious. A traditional system may approve this as it is within the set limits. However, by using behavioral analytics this can be identified as there are several unusual indicators. Depending on the banks security policies, this may cause the customer to have to verify their identity, their transaction may be blocked temporarily or they may need to confirm with the customer. By using traditional and behavioral analytics banks can get a better understanding.
Artificial Intelligence and Machine Learning
AI and machine learning have helped to enhance behavioral analytics. This means banks can analyze large amounts of customer data. Machine learning can analyze previous transactions, log-ins, device details and account activity to help identify behavioral patterns. As more data is analyzed they can identify any new unusual patterns. For example, an intelligent system can identify that several normal looking transactions are actually unusual when put together. This is especially useful for identifying more sophisticated fraud attempts. Whilst machine learning can help, they still need accurate information, to be regularly reviewed and monitored appropriately.
Challenges and Privacy Issues
Whilst behavioral analytics can help, there are some challenges with using this. As banks will be collecting and analyzing sensitive data such as account activity, transaction history, device details and customer interaction, there can be privacy issues. Whilst this can help prevent fraud, if too much data is being collected it can cause privacy issues. Financial institutions should ensure behavioral analytics is being used in line with data protection policies. They should ensure they are collecting data for legitimate reasons. Sensitive customer data should only be accessed by authorized staff and should be encrypted, stored correctly and protected with appropriate security measures. This will help customers understand how their banking information is helping to prevent fraud without affecting their privacy.
False Positives
Sometimes behavioral analytics can flag up legitimate customer activity as unusual. Customers may be travelling overseas, buying something expensive, replacing their mobile phone or making an emergency payment. This may cause them to suddenly have unusual activity, if banks consider everything unusual as fraudulent this can cause the customer issues such as the transaction being declined, their account being blocked and them having to verify. This can cause the customer to lose confidence. To reduce the chance of false positives, banks should look at several risk indicators. Whilst a customer logging in from an unusual location may not be a reason to block their account, if they are logging in from an unusual location, using an unknown device, making fast payments and changing their account settings this can be a bigger indicator. By looking at this in context, financial institutions can identify if there really is a threat.
Human Oversight
Whilst behavioral analytics can quickly identify any suspicious patterns, it is important to have human oversight. Whilst unusual patterns can be identified by automated systems, they may not understand the personal reasons behind customer transactions. For example, someone may suddenly make a large payment due to buying property, a medical emergency or a business deal. Without considering the reasons behind this, an automated system may flag this up as fraudulent. Banks should have processes in place to allow their security team to review any key alerts. They should look at any evidence and contact the customer using verified communication. This is especially useful if the alert may cause their account to be blocked. By combining automated systems with knowledgeable humans, banks can make more balanced decisions when preventing fraud.
Conclusion
Overall, behavioral analytics can be an important tool to help banks identify any suspicious activity from customers. By looking at unusual log-in locations, unexpected device changes, unusual payment amounts, fast payments and suspicious account changes, financial institutions can identify any warning signs. This will be more effective if combined with AI, traditional fraud detection, customer verification and appropriate human oversight. It is important to make sure that behavioral analytics is used with care to avoid any privacy issues. Banks should ensure they aren’t making decisions based on one behavioral change. They should look at several indicators to help make a decision. By doing this, financial institutions can help improve account security, spot potential fraud quicker, reduce unnecessary disruptions to transactions and provide a more secure and reliable digital banking experience for their customers.
Get more well researched information about Behavioral Analytics in Banking here.