Introduction
A major issue within the banking industry is financial fraud. With more banking being done digitally, customers are using mobile banking apps, internet banking, automatic payments and electronic payments. While these are convenient and fast ways to access your money, they have presented an opportunity for criminals to commit sophisticated fraud. As criminals are constantly finding new ways to commit fraud, traditional methods of detecting fraud are no longer as effective. Many banks are using AI and ML to help prevent fraud. These technologies can analyze lots of financial transactions, spot any customer unusual activity and identify suspicious behavior. Smart technologies can learn from the transactions and help banks prevent any financial loss.
Understanding AI
Artificial intelligence is computer systems that can carry out tasks that would normally be done by humans. This could be pattern recognition, analyzing information, predicting outcomes and providing support for decision making. Machine learning is a type of AI that allows computer systems to learn from past data and improve without having to be told by programmers what to do. Using AI in banking can be very beneficial as banks process thousands or millions of transactions. Without AI, each of these transactions would need to be analyzed manually which would take a lot of time, effort and resources. However, using AI to detect fraud can analyze the transactions, customer information, account activity and payment history in seconds. It can compare this to previous patterns and decide whether the transaction looks genuine or suspicious. If it detects any potentially fraudulent behavior it can alert, risk rate and suggest further checks.
Identifying Suspicious Transactions
One of the most important uses of AI in banking is identifying suspicious transactions. Every customer will have their own patterns when making transactions. This could be based on their income, how much they spend, how frequently they send money, where they are sending it to and how they use their account. AI will look at these patterns and use them as a benchmark. For example, if a customer that usually sends small amounts of money suddenly tries to send several large amounts to unknown accounts, the system will flag this as suspicious. The system can also look at where the transaction is coming from, what payment method they are using, how frequently they are making payments and other relevant information. Unlike traditional systems, AI can look at multiple factors. This means that banks can identify potentially fraudulent transactions.
Unusual Customer Behavior
Fraudsters will often try to mimic genuine customers by accessing their account, changing their personal details or making payments that don’t fit with their usual activity. Spotting unusual customer behavior is an important part of preventing fraud. AI will look at how the customer usually interacts with their account. This could include when they log in, how much they are spending, what devices they usually use, where they are located and how they like to pay. If their behavior changes suddenly, the system will notice the difference and see if any extra security checks are needed. For example, if the customer usually logs into their account from one location but suddenly tries to log in from another country on an unknown device. While this doesn’t necessarily mean they are fraudulent, it can highlight any security risks. By understanding what the usual red flags are and what unusual behavior customers can exhibit, banks can improve their investigations by using AI to spot any patterns.
Machine Learning and Account Takeover
Account takeover is when criminals gain unauthorized access to someone else’s account. This could be due to stolen passwords, phishing emails, hacking devices, social engineering or other methods of gaining login details. Using machine learning banks can identify if there may be an account takeover. The system will look at login activity and see if there are any changes to the usual account activity. For example, if the account has had multiple failed logins and then successfully logged in on an unknown device, the AI can detect this as suspicious. It can link the information together and realize that this may be unauthorized access. Depending on the banks security policies, it may stop the transaction for a short period of time, ask for extra ID checks or notify the security team. This can help the banks act quickly to prevent criminals taking any money.
Predictive Analytics
Another important piece of technology used in AI for fraud prevention is predictive analytics. This looks at past information and uses statistical models and machine learning to predict the probability of something happening in the future. Banks can use this to look at previous fraudulent activity and understand what factors are commonly linked to financial fraud. This could include unusual transaction frequency, suspicious payment destinations, unusual account activity and frequent attempts to access financial services. AI can learn from previous cases and identify any warning signs in new transactions. For example, if the payment shows similarities to previous fraudulent transactions, it may assign it a high risk rating. While not all fraudulent activity will be identified, it can help banks move from reacting to fraud to anticipating possible threats.
Anomaly Detection
Anomaly detection is a type of machine learning that looks for activity that doesn’t fit with the usual patterns within data sets. This can be very useful within banking as fraud isn’t always predictable. Some criminals will intentionally keep their transactions under the set security limits or use genuine payment methods to avoid being detected. Anomaly detection looks at multiple factors within financial activity. This includes transaction amount, frequency, account location, recipient and spending. It can then identify any activity that doesn’t seem to fit, for example, if the customer usually makes 2 or 3 transactions per day, but suddenly makes multiple transfers in a short period of time. An AI can recognize this and highlight the account. Banks can use supervised learning (using labeled examples of genuine and fraudulent transactions) and unsupervised learning (identifying unusual patterns).
Automated Risk Rating
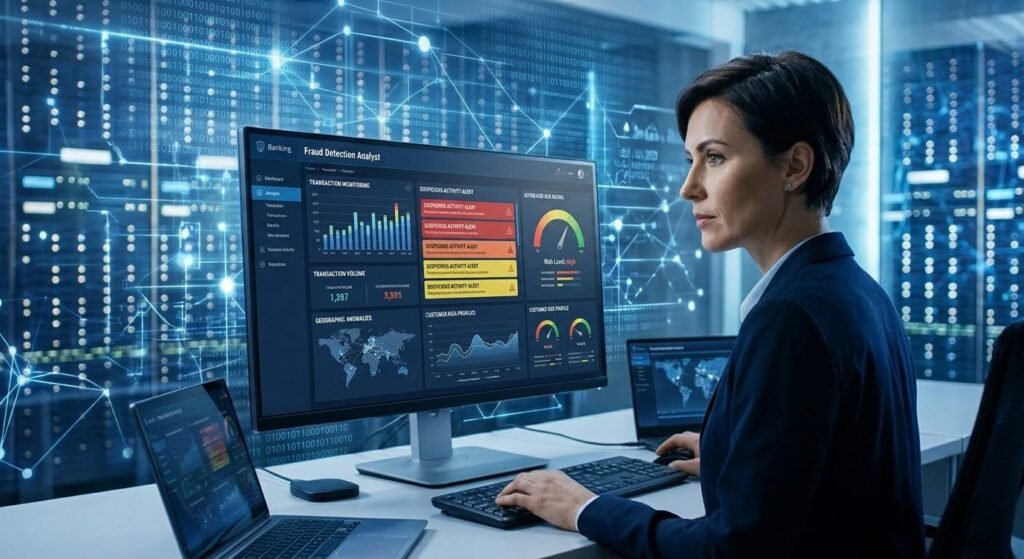
Automated risk rating allows banks to rate transactions based on the likelihood of them being fraudulent. The AI will look at multiple factors within the transactions and assign a risk rating. This could include transaction amount, recipient, device information, customer history, login location and recent activity frequency. If there are multiple suspicious factors within the transaction it may receive a high risk rating. If the activity fits with the customer’s usual behavior it may receive a low risk rating. Banks can use the risk ratings to decide how to deal with different transactions. Low risk payments can be processed normally, medium risk may require extra ID checks and high risk may be stopped for a short period of time or sent to the fraud investigation team. This can help banks prioritize any suspicious activity, make efficient use of their investigative resources and make quicker decisions.
Real Time Fraud Detection
Real time fraud detection is very important within modern banking. As payments can be made electronically in seconds, it is important to detect fraud as soon as possible. AI can help by analysing transactions. When a customer makes a payment, the system can look at the relevant information. It can then compare this to usual transaction patterns and calculate the risk. If the payment appears to be suspicious, the bank may ask for a one time password, biometric verification or other forms of verification. In more serious cases, the transaction may be rejected or stopped for investigation. Real time monitoring is important for mobile banking, card payments, online purchases and instant payments.
Benefits of AI Fraud Prevention
Using AI can provide many benefits for banks. Firstly, it can increase the speed of detecting fraud. As AI can analyze lots of transactions much quicker than manual investigations, banks can identify suspicious activity. Secondly, it can increase accuracy. As AI looks at multiple factors within transactions, it can provide accurate results. Thirdly, machine learning can adapt to new patterns as more information about transactions can be provided. Another benefit is increased efficiency. AI can automatically flag high risk activity, meaning less transactions need to be looked at manually. This means the fraud investigation team can focus their efforts on more serious cases. This can also increase customer confidence as customers are more likely to trust banks that can show they are protecting their accounts and financial information.
Avoiding Inconveniencing Genuine Customers
While fraud prevention is important, banks should ensure they aren’t causing unnecessary issues for genuine customers. False positives can occur when genuine transactions are flagged as potentially fraudulent. For example, if a customer is abroad suddenly using their bank card in another country it may look unusual. Or if a customer is making an unusually large purchase it could trigger a fraud alert. Having too many false positives can cause payments to be rejected, accounts to be blocked, payments to be delayed and cause customer dissatisfaction. AI can help reduce this by looking at multiple factors and looking at individual customer behavior. Banks can also implement additional checks along with automated detection.
Limitations
There are some limitations to using AI for fraud prevention. Firstly, the quality of data, machine learning requires accurate, relevant and varied data to correctly identify fraudulent activity. If the data isn’t complete, up to date or biased the results may not be accurate. Secondly, financial crime is constantly changing. Criminals regularly come up with new methods so banks must update their models. AI can cause false positives and may not be able to identify sophisticated fraudulent activity. Finally, implementing advanced fraud detection technology can be costly. This could include investing in software, infrastructure, cybersecurity and skilled staff. Banks must also ensure they are protecting sensitive customer data and following data protection and financial regulations. This shows that AI should be used to help with effective fraud prevention strategies and shouldn’t be left unmonitored.
Human Oversight and Strong Cybersecurity
Even with advanced AI, it is important to have human oversight whilst detecting financial fraud. While smart technologies can analyse information and identify suspicious patterns, human investigators are needed to look into complex cases. They can understand why there may be unusual circumstances and make informed decisions. Fraud investigation teams can look into flagged transactions, contact affected customers and decide whether the activity was genuine criminal activity. AI models should be regularly tested to identify any weaknesses. Cybersecurity should also be strong as fraud prevention technology can be targeted by cybercriminals. Banks must ensure that customer databases are protected, unauthorized access is limited, communication is secure and monitoring systems are reliable. By combining AI with skilled staff, effective internal controls and strong cybersecurity policies, banks can create a more comprehensive fraud prevention strategy.
The Future of AI
In the future, financial fraud prevention is likely to become more advanced with more AI, advanced machine learning, behavioral biometrics and real time data. As digital banking becomes more popular, banks will need more intelligent systems to help identify complex threats. Behavioral biometrics can look at how customers interact with their devices. This could include how they type, mouse movements and touch screen. This can help determine whether the customer is likely to be the genuine account holder. More advanced AI can also help banks identify links between suspicious accounts, recipients and co-ordinated fraud. However, responsible data handling should be considered. The models should be regularly tested. Banks that invest into these areas will be better prepared to handle new threats. They can also ensure they are providing reliable digital services and protecting customer data.
Conclusion
Artificial intelligence and machine learning are transforming the way banks detect, investigate and prevent financial fraud. Using suspicious transaction monitoring, behaviour analysis, account takeover detection, predictive analytics, anomaly detection and automated risk rating can help banks identify potential threats quicker. The ability to analyze large amounts of information in real time can improve efficiency. However, AI isn’t perfect. There are issues with data quality, false positives, constantly changing criminal tactics, cost of implementation and customer privacy. These should be managed effectively. Human expertise is also required to look into complex cases. The most effective fraud prevention strategies will include intelligent technology, strong cybersecurity, reliable customer verification and human judgment.
Get more well researched information about AI Fraud Detection in Banking here.