Introduction
Cloud computing has become a key enabler for banks and financial institutions to handle information, provide services and support their technology bases. The traditional approach of banks was to host their main systems on physical servers and data centers located on site, with the use of expensive hardware. These tended to give direct control over technology resources but were often accompanied by a significant investment, long maintenance procedures and complex upgrade. The basis of cloud computing is providing financial institutions with computing power, storage, databases and software over the internet and remote infrastructure. This can help to deliver faster services, flexible resource allocation, and efficient data management. Moreover, by enabling financial institutions to modernize banking operations, integrate digital services, and effectively address evolving customer expectations, while still adhering to the necessary security and regulatory standards, the adoption of cloud-native banking platforms is aiding in the evolution of banking operations. The implementation of cloud-native banking platforms is helping financial institutions modernize banking operations, integrate digital services, and adapt to evolving customer expectations while maintaining the appropriate security and regulatory controls.
Cloud Computing and its Application to Financial Services
Cloud computing means providing technology services via a network, instead of having to have all the technology components in the organization’s facilities. Cloud services can be leveraged to run applications, manage customer data, handle payments, analyze financial transactions and enable digital banking channels for banks. They can lease infrastructure, access a managed databases, or have access to a full software application from cloud vendors, depending on their need. This flexibility enables financial institutions to focus more on their customers, product development and risk management, rather than on routine hardware maintenance. But the shift to the cloud does not shift the bank’s obligation to safeguard consumer data, ensure its financial records are accurately maintained, or adhere to relevant laws and regulations. Financial institutions need to be cautious in evaluating providers, defining security responsibilities and ensuring outsourced technology services are as reliable and secure as financial institutions expect.
Application of Cloud Computing in Banking
Hosting Banking Applications
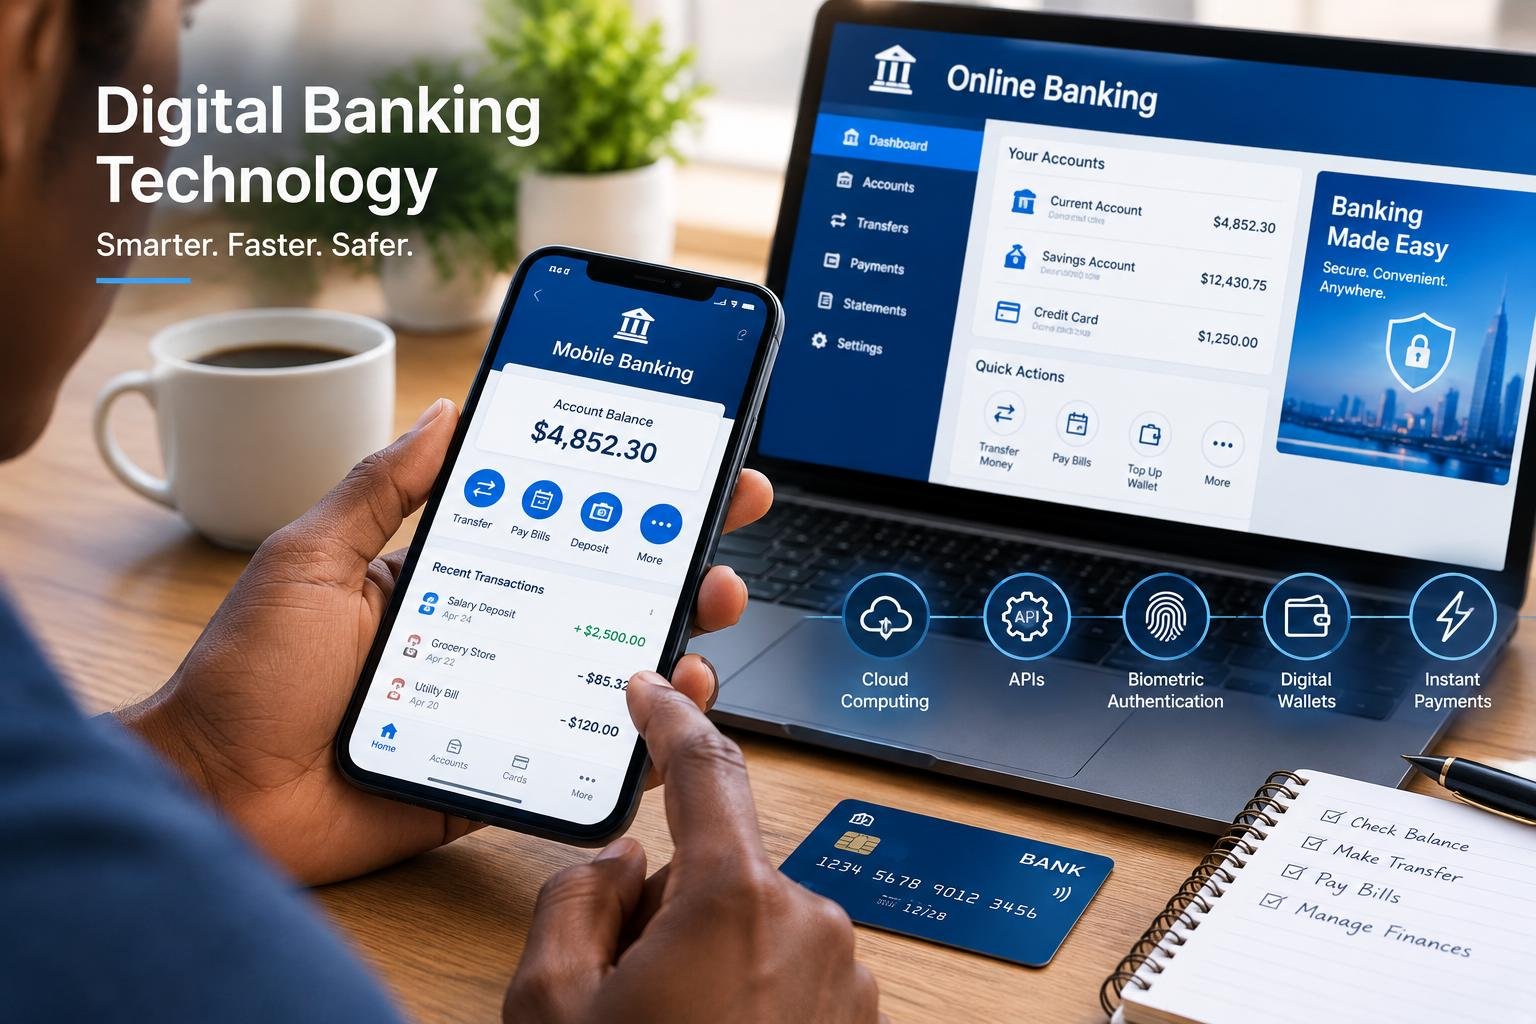
These cloud-based solutions are found in banks to deliver internet banking, mobile applications, customer relationship management, payment services and in-house enterprise applications. An institution does not need to buy and manage all the required servers, but can run applications on a virtual machine, container or managed platform provided by the cloud. These resources are used for various crucial activities like checking account balances, answering account queries, notifying the user of transactions, and enrolling them as a customer. Cloud hosting can also make it easier to integrate financial applications with payment gateways, as well as identity verification and third-party financial services by using application programming interfaces (APIs). However, critical banking applications need to be well designed, monitored and restricted. Institutions will need to identify workloads that can be moved to the cloud and then ensure that the critical transaction systems will continue to be available, consistent and have the response times necessary to ensure reliable financial operations.
Financial Information Storage and Analysis
Financial institutions collect massive amounts of data as a result of their operations, customer interactions, payment transactions, investment activity, and the digital interactions. Cloud storage ensures scalability when it comes to keeping this information, and cloud analytical services enable organizations to process vast amounts of data without adding to the number of devices they buy. These capabilities guide banks through suspicious transaction identification and credit-risk assessment, customer behavior analysis, cash-flow prediction, and financial reporting. Machine learning tools can look for patterns that may not be easily discernible with manual methods, aiding risk and compliance teams to uncover unusual activities. But the financial information should be safeguarded by using encryption, access control, retention policies, and data classification. Institutions need to also determine how information will be stored, what users are permitted to access and if it will be processed in accordance with privacy laws and financial-sector requirements.
Scaling Digital Banking Services
Banks can see a surge in customer demand for banking services at certain times of year, such as payday, promotions, market volatility and during significant payment events. When the demand for infrastructure services, such as those provided by banks, is higher than usual, banks have to buy additional hardware to cope with the surge in demand, but during low traffic times, a significant portion of that capacity might not be utilized. Cloud computing enables institutions to upscale or downscale their computing infrastructure to meet demand as needed, while keeping infrastructure costs in check and performance high. For instance, if a mobile banking app has to deal with a surge in transactions, it could selectively deploy extra computational resources, and release idle resources during periods of low demand. This elasticity can facilitate digital growth, and it could reduce the need to rely heavily on long hardware procurement cycles for the introduction of new products. But scaling needs to be planned carefully otherwise there can be bottlenecks even with the extra cloud resources thanks to the limitations of databases, third-party payment networks, software bugs or poorly configured services.
Comparing Public, Private, Hybrid and Multicloud Environments
The security requirements, regulatory needs, current technology, and end goals of financial institutions can vary, which means they may have different cloud deployment needs. Public clouds are computing resources delivered by external providers to multiple customers that are logically separated. They provide a wide range of services, scaleability and advanced technologies without banks having to maintain a large-scale infrastructure. Private clouds isolate an environment for a single organization, may offer more control over configuration, policies and sensitive workloads, and can be more costly and require more management. Hybrid cloud is a mix of both private and public clouds, enabling banks to keep certain critical systems on private cloud while transferring other apps and analytical workloads to public clouds. Multicloud is the use of services from more than one cloud provider, which can help to decrease the reliance on a single vendor and provide institutions with access to a variety of technical capabilities. But running multiple environments can add to integration complexity, security issues and operations costs. Banks should, therefore, choose the right approach if it’s proven to be useful for their business and not simply because it’s the safest or most efficient that could be.

How Cloud-Native Banking Platform Accelerate Innovation.
The cloud-native banking platforms are built with technologies like containers, microservices, automated deployment pipelines and orchestration tools to benefit. Rather than develop and deploy a single tightly coupled banking application, the developer can break up functionality into separate services to be developed, tested, deployed and scaled independently. For instance, payment processing, customer notification, account management and fraud monitoring could all be separate modules with secure communication interfaces in between. This type of architecture can enhance the speed with which you can roll out new functionality and the ability to update services while maintaining the entire application without rebuilding. Continuous integration and automated testing also enable development teams to find defects at an earlier stage and to provide improvements at a more frequent rate. But, cloud-native systems demand some specialized engineers, robust monitoring, efficient configuration management, and adequate software dependency management.
Disaster Recovery and Operational Resiliency.
Failure of hardware, cyber-attacks, power outages, natural disasters and other disruptions can occur in any bank and must be prepared for. By enabling institutions to duplicate data, keep backup environments and restore applications at alternate sites, cloud computing can be a powerful tool in reinforcing the DR process. A bank can recover services through a standby infrastructure or spread specific services across multiple availability zones and/or regions, depending on the architecture. Automated backups and recovery can help minimize the recovery time of critical systems after an incident. Cloud monitoring can also enable operational teams to detect abnormal activity and performance issues before they become significant issues. But keeping backups in the cloud does not ensure that they can be retrieved. Banks need to exercise the following measures: test bank restoration procedures, secure backup credentials, prevent backup data being tampered with by unauthorized users, and set realistic recovery time and recovery point goals. There should also be operational resilience plans in place for providers’ outages, telecommunications outages and issues with systems outside of the cloud environment.
The Essence of Cybersecurity: Controls and Regulatory Compliance
Financial cloud adoption places precious financial data including personal information, account information, payment details, and commercially sensitive information at risk, which is why cybersecurity is still one of the top concerns. Banks should deploy end-to-end data encryption, implement multiple-factor authentication, user access controls and have a centralized security event monitoring system in place. Privileged accounts must be specifically protected due to the fact that an attacker that gets access to a privileged account can use it to access crucial systems or confidential documents. Institutions can also perform vulnerability assessments, keep software up-to-date, manage third-party dependencies and have incident response plans. Cloud services are often delivered based on a shared-responsibility model, where the cloud provider secures the infrastructure, while the customer is responsible for a wide range of elements of their applications, data, identities and configurations. The division will be based on the service being provided. Banks need to be aware of contractual obligations and should ensure that they have evidence that appropriate controls are in place and are working effectively. They will also have to review outsourcing policies and procedures, audit access, data retention, privacy, and security incident reporting policies and procedures.
Data Sovereignty and Vendor Dependency
Data sovereignty is the legal and regulatory considerations related to data which depend on its location, where it is stored, processed and accessed, and that are applied to it. The whereabouts of customer records may have implications for financial institutions with regards to privacy obligations, supervisory access, cross-border transfers and contractual commitments. Banks are advised to know where the cloud providers have their data centres, how the backups are distributed and who could have access to information for operational support. These concerns can be alleviated by institutions implementing regional hosting options and by contractual safeguards, but institutions must ensure that the arrangement meets the rules that apply to the institution’s operations. Another obstacle to overcome is vendor dependence, as applications, data formats, proprietary services, and specialized cloud tools can add up to costly and complicated migration to a different vendor. Banks can minimize this risk by having exit plans in place, data application architectures that can be moved to other banks, standard data formats and regular testing of the data export process. While there are benefits to using a multi-cloud approach, the cost of using it needs to be taken into account alongside the management and integration tools required.
Challenges and Best Practices of Cloud Migration
Cloud-based banking is not about simply moving on-premises applications to the cloud. Before institutions can safely migrate, they need to evaluate their infrastructure, find out which systems are dependent on others and classify the information, and identify the systems they can safely move. Cloud applications may depend on specific hardware, legacy software, or highly coupled databases that need extensive reengineering to make them cloud-ready. Older core banking applications might be on special hardware, have legacy software or coupled databases with a significant amount of reengineering required for the cloud. A phased migration can help minimize risk by prioritizing workloads that can be migrated first, testing and addressing performance issues, and addressing security and compatibility issues before migrating the more critical workloads. Banks should have transparent governance, track the expenses of the cloud, educate staff and give ownership for keeping each service running. They should also perform integrity and recovery tests, along with heavy workload access controls and performance. With close collaboration with regulators, auditors, technology suppliers and internal risk specialists, migration decisions can be made that will provide for long term stability of operations and not just for short term cost reduction.
Conclusion
Cloud is transforming banking by offering scalable app and data infrastructure, analytics, digital application services, software development and disaster recovery. It can enable financial institutions to respond faster to customer requirements, innovate with new products and adapt to increasing and decreasing volumes of transactions without being dependent on conventional data centres. The various models of public, private, hybrid and multicloud environments come in a variety of possibilities of control, flexibility, complexity and cost, so it is important to carefully choose which one to use. Meanwhile, cloud adoption brings with it new challenges in cybersecurity, regulatory compliance, data sovereignty, vendor reliance and operational resiliency. Good governance, recovery capabilities, security measures and migration planning are important for successful implementation. With the right precautions and controls in place, banks or other financial organizations can take advantage of cloud computing to improve the way they run their business, safeguarding the information assets of their customers and keeping their service reliable to the expectations of financial services.
Get more well researched information about Cloud computing in banking here.