Introduction
Artificial Intelligence has been revolutionizing the financial landscape by making it possible for financial institutions to quickly analyze information, identify patterns, and make decisions. It’s an incredible transformation in the financial industry, and AI is currently assisting monetary establishments in analyzing data, recognizing trends, and making speedy choices. Conventional financial systems tend to rely on pre-determined rules and manual evaluations, and may fall short of being able to handle huge amounts of data in real time. With AI, machine learning, predictive analytics, and NLP capabilities are added, improving financial operations’ speed and accuracy. Examples of these technologies are fraud detection, credit assessment, investment management, customer service and market analysis. They also feature in algorithmic decision making in which decisions are recommended or made by a computer system, which is based on a set of data and set of rules. While AI has many benefits, it is important that it is underpinned with good data, right safeguards, clear processes, and human supervision.
Artificial Intelligence in the Finance Sector
AI in finance refers to financial computer systems that are leveraged to perform tasks that typically require human intelligence, including learning from previous data, comprehending language, finding patterns and making forecasts. One of the crucial parts of that is machine learning, which enables the systems to learn and adjust their behavior based on the patterns that they find in the data and information that they have, in order to evolve their behavior, rather than being, strictly speaking, programmed. The bank may leverage a pattern of the borrowers’ loan applications in order to build a model to forecast if the borrower of a new loan will or will not repay their loan. Similarly, a trading company can look at the years of market data and find out the circumstances that lead to price changes. These systems analyze data from various sources, such as transaction logs, economic data, customer interactions, and financial statements. Their recommendations might help to inform employees and to streamline some processes, but are not predictions. Hence, the financial institutions should periodically test their models, and ensure that automated systems are applied within the scope of the legal, ethical and operational considerations.
AI-Driven Fraud Detection and Suspicious Transaction Monitoring
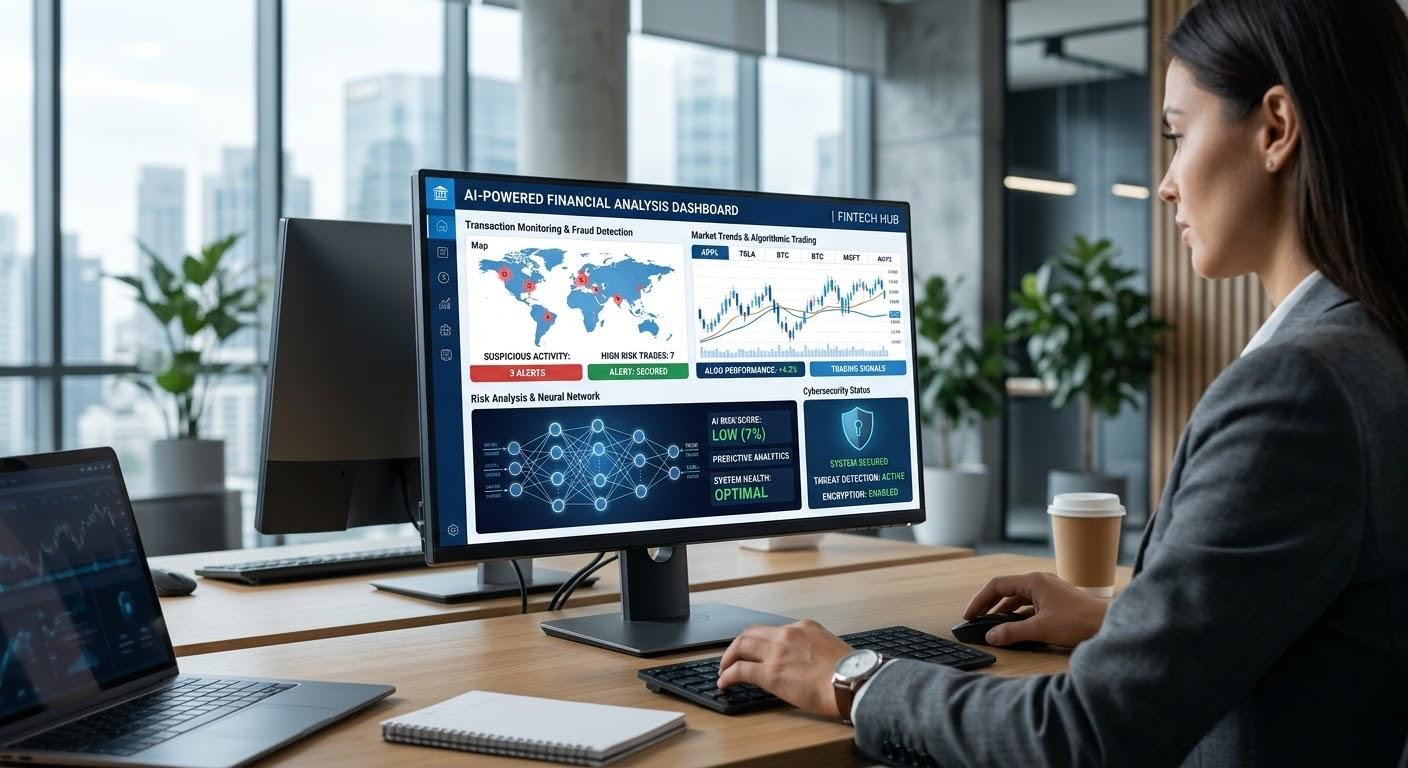
One of the most crucial areas where AI is being used in finance is fraud detection. Traditional monitoring systems can’t catch all suspicious activity in banks and payment providers, as they make thousands or even millions of transactions. Transactions amount, location, payment time, device, account history, and spending behavior can be analyzed using machine learning models to detect unusual behavior. An AI system can detect, for instance, an individual making multiple high-dollar transactions from various countries, which could be an indicator for the security system to require further verification from the customer. Some models rely on a supervised learning approach (supervised), which is training a model on a set of previously labeled transactions that are fraudulent or not. Others apply anomaly detection to detect strange behavior, not needing all the anomalies to be known beforehand. Real-time analytics can help financial institutions verify transactions as they happen, preventing unauthorized transactions and/or sending for further identity verification prior to the transfer of funds.
But, fraud detection solutions need to strike a balance between security and convenience. Customers may be traveling, buying a high dollar product or using a new device, all of these may appear as an unusual transaction. Too many false alarms could delay payments, cause customer frustration and burden fraud investigation resources. Criminals also change their tactics to beat the system; this is why institutions need to continuously adapt and update their models and monitoring systems. Systems that are effective, then, combine an automated risk score with transaction limits, identity verification, investigation processes and human review, if required. Additionally, sensitive information that are utilized for training and operating their models should be protected by institutions. Financial institutions can leverage machine learning with existing security measures to better detect unusual transactions while not assuming that those are actually fraud attempts.
How to Employ Algorithmic Trading and Investment Automation
Algorithmic trading involves the use of computer programs to interpret the financial markets and carry out trades based on certain rules or signals developed by the algorithm. By analyzing old price data, trading volume, economic news, company reports and more, that can affect price movements, AI can reinforce these systems. Machine learning models can be used to uncover patterns or relationships between market conditions and asset prices, and predictive analytics can help predict the likelihood of specific outcomes. For example, a trading system may identify a change in the trading volume and/or the relevant company statements and trigger a signal for further analysis. A trading strategy can then be activated with this automated process when certain price, risk and liquidity parameters are met. AI can also aid in portfolio rebalancing by analyzing and comparing the current investment mix to the desired allocation, and making recommendations for rebalancing it toward the goals. These features assist investment companies to handle data quickly and successfully cut down the time it requires to carry out duplicate calculations.
However, algorithmic trading is not an assured way of profitable investments. Unexpected events, fluctuations in investors’ confidence, political changes and economic shocks, some of which may not be accurately predicted by historical data, impact financial markets. Models that work well in one market can be of little value in another. Automated trading can also lead to magnified losses when the systems generate excessive trades when the timing is wrong, technical issues arise, or trades execute in illiquid markets. Institutions thus need to set up position limits, loss controls, monitoring procedures and emergency shutdown mechanisms. The human supervisor should be familiar with the purpose of this strategy and what its limitations are, and then have to examine its performance and intervene when it falls outside acceptable parameters of market behavior. A key strength of AI is its ability to assist in disciplined investment processes, not to supplant risk management, which requires careful consideration of numerous factors, including human expertise. A major advantage of AI is that it can aid investment processes, not replace them; it cannot replace risk management, which requires taking into account many factors, including human expertise.
The use of AI in Financial Risk Analysis and Credit Risk Assessment
In a credit risk assessment, the credit risk is estimated by estimating the probability of a borrower to fail to pay his financial debt. The usual ways of obtaining the credit history and income details, debts, employment information and existing scoring models have been followed by lenders for a long time. These and more legally-allowed data types can be used by AI to correlate data in ways that can enhance risk estimates. A lender could, for instance, employ machine learning to contrast the histories of paying back of borrowers who fit in various income ranges, debts, and credit records. Predictive models can then predict the risk of default, and inform the decision of whether or not to further assess an application. AI can also be applied to financial risk analysis on a wider scale, as it can take into account market volatility, market short-term liquidity exposure, changes in the interest rate level, and even losses in various economic scenarios. The same techniques can be applied to insurance companies to estimate claims risk, or to the banks to detect customers or portfolios that need more attention.
Even though these advantages, credit models can be used to create patterns that are unfair in the past. A model trained on past lending decisions may perpetuate or exacerbate the disadvantaged status of a group based on the past decisions. Sensitive personal traits can be reflected in seemingly neutral variables. The uncertainty of information, small training sets, and shifts in economic conditions can also result in poor evaluations. Financial institutions should conduct tests of models that can have disparate impacts, consider the suitability of data, make decisions about discriminatory outcomes, and ensure that there are methods for customers to challenge inaccurate data. When the automated assessment might have a substantial impact on a person’s access to credit, housing financing or any other vital financial opportunity, human review is especially crucial. Responsible risk analysis is a perfect blend of predictiveness, fairness, regulatory compliance, and easy procedures for error-correction.
Developing a Strategy for Integrating NLP and AI in Customer Service
Natural language processing (NLP) is a technology that allows computers to understand and create natural language, which can be applied in customer support and financial information analysis. AI chatbots and virtual assistants process and respond to frequently asked banking questions, such as checking account balances, transaction statuses, payment processes, card security, and service availability. For instance, if someone wants to know why their transfer is delayed, they can get the help of a chatbot without waiting for a human representative to help them out. Another great use of NLP systems is to summarize financial reports, analyze customer feedback, identify common problems, and get useful information from long documents. Language analysis can be employed by investment professionals to analyze business announcements, earnings reports and economic news that can impact investor expectations. The applications that these tools support are designed to assist organizations to handle massive amounts of unstructured text and make information readily accessible. Language models can, however, misinterpret questions, provide incorrect explanations, or provide plausible yet incorrect answers. The financial institutions should, therefore, avoid using automated systems for tasks that are not appropriate, use appropriate systems to safeguard customer data, and escalate important financial matters and transactions or complaints that require special attention to human-level staff.
Ethical restrictions, Data Quality and Cybersecurity
While AI can enhance financial oversight, it also brings in technical and security issues. The quality of data plays a critical role in models, and incomplete, out-of-date, inaccurate, or manipulated data can compromise model predictions. Cybercriminals can try to exploit any vulnerability in the automatic systems, access valuable training information or tamper with the data fed into the systems, or even make unauthorized entry into the connected financial infrastructure. However, institutions that fail to keep backups, access controls, and incident-response plans will create new operational dependencies with the use of AI tools. The other issue is explainability, some models are complicated and make predictions that, while accurate, do not give a clear explanation to the customers, auditors or regulators. When making decisions with automated systems, it may be challenging to determine who is at fault for the mistake or if someone was at fault. The financial institutions can utilize encryption, robust authentication mechanisms, access controls, external security audits, ongoing monitoring and periodic model assessments. They should also be able to record the training of the systems, define the responsibility for the results of the systems and have procedures for reporting and correcting the failures. AI governance is not about adding security, privacy, fairness, and transparency features to the mix; it is about making them core features.
Importance of Human Oversight and Responsible Implementation
Adopting AI is not simply about purchasing cutting-edge technology; it’s about making it effective. Before deploying models into actual operations, financial institutions need to identify the right scenarios for use, define specific goals and targets, assess the available data, and perform models. They should check the results of the automated process against known methods, track error rates, and evaluate if performance would be reduced if the customers’ behavior or market conditions changed. There are certain high-risk situations where human intervention is crucial, such as approval of credit, when financial crime is suspected, exposure to investment or access to critical services. Fewer employees require adequate training to understand the output from the models, understand uncertainty, and question recommendations that are in conflict with reliable evidence. Institutions should also have set procedures that designate the next steps to be taken if unusual cases are discovered, rather than automatically going through the process. AI-powered automated analysis can be implemented along with professional judgment, documented controls, and periodic independent reviews to provide benefits for the organization without the risk of unfair treatment, avoidable losses or disruption to their operations.
Conclusion
AI is revolutionizing finance with its ability to detect fraud quickly, provide timely customer support, analyze credit risk patterns, drive algorithmic trading, and perform sophisticated risk analysis. Machine learning can assist institutions in understanding patterns in intricate data and natural language processing can simplify the understanding and use of financial information. Efficiency decreased repetitive tasks and better-informed decision making can be achieved through real-time analytics and selective automation. But AI systems can still be susceptible to biases in data, erroneous forecasts, cyber security risks, and unforeseen shifts in financial markets. When considering their recommendations, therefore, it is essential that they are considered carefully, particularly in regard to either people’s financial opportunities or the significant investment risks. The best solutions involve using a trusted technology, responsibly managing data, maintaining clear processes, ensuring regulatory adherence, and having human oversight. AI, if harnessed properly, can enhance financial practices without sacrificing the element of fairness and accountability or inundating the workplace with efficiency at the expense of human judgment.
Get more well researched information about Artificial Intelligence in Finance here.