Introduction
To accurately understand a company’s financial position, and to allow informed business decisions to be made, accurate accounting must be performed. However, it is very easy to make mistakes in accounting. Recording the wrong account or amounts may cause errors within the accounts. In order to ensure that accounting is as accurate as possible, businesses carry out a number of checks. A Trial Balance is carried out to ensure that the totals of debit and credit balances within the General Ledger are accurate. By compiling information from individual accounts in the General Ledger, we can obtain an overview of the business’s financial activity. In addition, the Trial Balance means that certain errors within the books can be found.
What Is A Trial Balance?
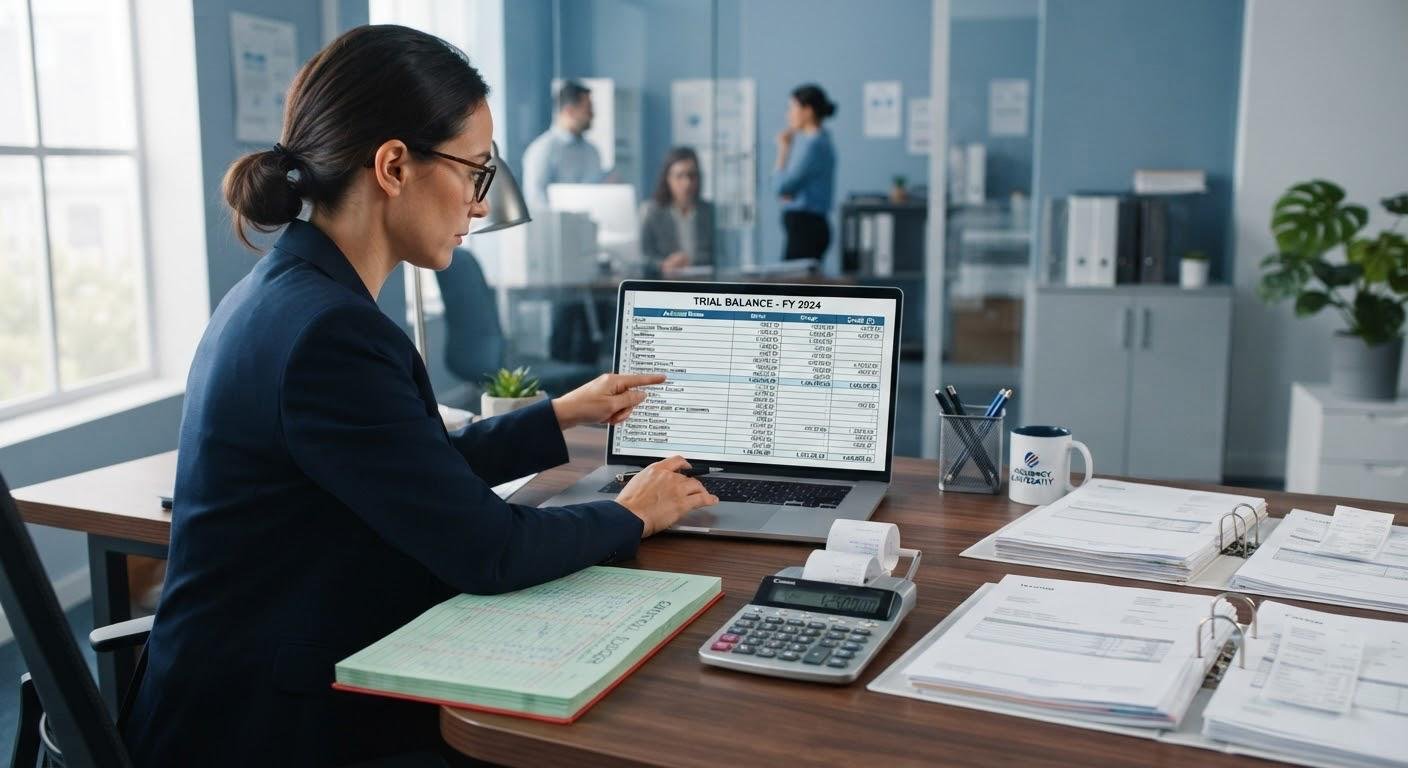
A Trial Balance is a document that shows the closing balances in all general ledger accounts. It divides different account balances into Debits and Credits. It allows accountants to verify that the total Debit and Credit balances are equal, as per the double entry system. All financial activity must affect 2 accounts, in equal amounts. For example, if a business buys equipment for their office with cash, the Equipment account is debited and the Cash account credited. This means that the overall accounting equation is balanced. As shown in this guide on Trial Balance in Accounting, a Trial Balance is an important step in the accounting process. It allows accountants to quickly check the balances in the ledger and find any potential errors before financial statements are produced.
Purpose of a Trial Balance
The key use of a Trial Balance is to verify that the totals within the ledger accounts are mathematically correct. Once produced, accountants check that the total debits equal the total credits. If they do, it indicates that the accounts are mathematically correct, although it does not guarantee that the transactions have been accurately recorded. Additionally, Trial Balances allow businesses to produce financial statements, such as income statements and balance sheets. By having all balances in one place, accountants can easily produce financial statements. It also makes it easy to spot unusual values, understand account activity and investigate discrepancies in accounts before producing final financial documents.
Debits and Credits
Within Double Entry bookkeeping, for every transaction there must be at least one debit and one credit in equal amounts. However, depending on what account is being used, a debit and credit will have a different effect on the value. Generally, assets and expenses will increase in value with a debit and decrease in value with a credit. Conversely, liabilities, equity and revenue accounts will increase with a credit and decrease with a debit. For example, if a company receives £500,000 from a customer, the Cash account would be increased (debited) by £500,000 and the Revenue account increased (credited) by £500,000. This means that the total Debits and Credits remain equal.
Trial Balance Preparation
To create a Trial Balance, information from the General Ledger is collated. Before a Trial Balance is produced, accountants must ensure that financial activity has been correctly recorded in the relevant journals, and transferred to the relevant accounts in the General Ledger. Within each account in the ledger, accountants must ensure that it is balanced by adding up the total debits and credits within that account. If the account has a debit balance, it will be added to the debit column. If it has a credit balance it will be added to the credit column. Once all relevant accounts have been added, accountants add up the totals in both columns. If they do not match, further investigation must be performed. Trial Balances are generally produced at the end of an accounting period. Sometimes, however, they will be made monthly or as required by managers.
Example of a Simple Trial Balance
At the end of an accounting period, the following balances were in a small business’ ledger. The Cash account had a debit balance of ₦300,000, the accounts receivable account had a balance of ₦150,000, the equipment account had a balance of ₦250,000 and the rent expense account had a balance of ₦50,000. On the credit side, the accounts payable account had a balance of ₦100,000, the owner’s capital account had a balance of ₦400,000 and service revenue had a balance of ₦250,000. The balances in each account were transferred to the Trial Balance. The totals were calculated and it was found that the total debit balance was equal to the credit balance (₦750,000). This means that the Trial Balance has been balanced. A Trial Balance like this allows accountants to easily check that balances in accounts are consistent.

Different Types of Trial Balances
There are 3 main Trial Balances that businesses produce. These allow accountants to check financial records at different points in the accounting process. Despite all Trial Balances comparing totals of debits and credits, the times they are produced and the adjustments made will be different. Knowing the differences between Trial Balances will allow businesses to keep records in order, and easily find errors before completing financial statements.
1. Unadjusted Trial Balance
An unadjusted Trial Balance is produced once all transactions have been recorded in the journals, and transferred to the General Ledger. It gives a snapshot of all accounts at the end of the accounting period. It can be used to check that the total debits equal the total credits, and any clear mathematical errors. However, some expenses and revenue may not have been recognized due to needing adjustment. For example, the business may have used electricity during the month; however, the electricity bill may not have arrived before the Trial Balance was made. This Trial Balance can be used as a starting point, and allows accountants to determine what adjustments must be made in order to produce accurate financial statements.
2. Adjusted Trial Balance
An adjusted Trial Balance is produced once necessary adjustments have been made. Adjustments may include accrued expenses, prepayable expenses, depreciation, accrued revenue and unearned revenue. These adjustments ensure that income and expenses are accurately recorded in the correct period, under the accruals basis of accounting. For example, if a business pays ₦120,000 for 12 months of insurance, only the cost of insurance applicable to the current accounting period should be recognized as an expense. The remainder should be kept in prepayments, an asset account. Once adjustments have been made, accountants will update the balances in the ledger, and produce a new Trial Balance. The information in this Trial Balance is much more accurate, and will be used to produce financial statements.
3. Post-Closing Trial Balance
A post-closing Trial Balance is produced once temporary accounts have been closed at the end of an accounting period. Temporary accounts include revenue, expense, and drawings/dividends depending on the business. The balances from these accounts are transferred into relevant permanent equity accounts, so that they start the next accounting period with a zero balance. The post-closing Trial Balance only includes permanent accounts. These include asset accounts, liability accounts and equity accounts. This Trial Balance allows accountants to verify that balances remaining in accounts are mathematically consistent. It also provides opening balances for the next accounting period. By analyzing this Trial Balance, accountants can ensure that records are ready for the next accounting cycle.
Common Errors Picked Up By Trial Balances
Despite improvements made by accounting software, errors in bookkeeping can still occur. Trial Balances can allow accountants to spot errors in accounting which caused the total Debits and Credits to be unequal. Common errors include omissions where one side of a transaction is not recorded. Transposition errors may also occur in accounts, where numbers have been put in the wrong order (such as, ₦5,430 instead of ₦5,340). Commission errors occur where a transaction has been entered into the wrong account within the same category. Finally, calculation errors may occur when calculating balances in accounts, or when putting values in the Trial Balance. These errors may cause the total Debits and Credits to be unequal in the Trial balance, so it can be a useful way of spotting issues in accounts.
Investigating and Correcting Inaccuracies in Trial Balances
If the totals in the Debit and Credit columns of a Trial Balance are unequal, accountants must carefully investigate the issue. To begin with, the totals should be recalculated to ensure that this issue in not due to a calculation error. Accountants may compare the information in the Trial Balance to the balances in the individual accounts in the General Ledger to ensure that all balances have been correctly transferred. If the discrepancy still exists, accountants should consider the journals, postings and supporting documentation (invoices, receipts, bank statements and payment records) to identify the issue. They should also look at unusual balances in accounts, and transactions that may have been incorrectly recorded. If necessary, accountants may trace the entries back to original documents, through the journals, and into the General Ledger. This investigation can help identify the real issue within the Trial Balance so that accurate corrections can be made, supported by reliable information.
Suspense Accounts for Unclear Issues
On occasions, accountants may be unable to identify why an imbalance in the Trial Balance has occurred. In this situation, accountants may put the difference in a Suspense Account. For example, if there is a ₦20,000 imbalance between Debits and Credits, with more Debits than Credits, accountants may put the difference into a Suspense Account to temporarily balance the Trial Balance. However, this does not mean that the issue has been fixed. The accountants must continue to investigate records to find the incorrect or missing entries. Once the error has been corrected with appropriate journal entries, the Suspense Account should have a balance of zero. Businesses should be careful not to leave any unclear balances in Suspense Accounts, as this could affect accuracy within financial reporting.
Limitations of Trial Balances
Trial Balances are not able to pick up on all errors. Even if Debit and Credit balances are equal, this does not mean that all transactions have been accurately recorded. For example, if a transaction is completely missed out in the accounts, neither the Debit or Credit columns will be affected. Therefore, the Trial Balance will still be balanced. Alternatively, a transaction may be put in the incorrect accounts. However, if the Debit and Credit values are equal within those accounts, this will not result in an imbalance in the Trial Balance. This is known as an error of commission/classification depending on how this occurred. Similarly, errors of principle may occur. In this situation, transactions may be entered in accounts which go against accounting principles. These issues mean that a balanced Trial Balance cannot be relied upon to ensure that financial records are completely accurate.
Another limitation of Trial Balances is that they do not ensure that transactions have been genuine, and have appropriate supporting documentation. False transactions or incorrect values may be entered, with equal Debits and Credits. This would still give a balanced Trial Balance. Furthermore, it does not independently verify that assets exist, liabilities have correctly been fully accounted for, or that balances can be recovered. For example, even if a business has a large balance of accounts receivable, some of these customers may be unlikely to pay. This would mean that the accounts receivable balance is unreliable. Without further investigation and adjustment, this issue will not automatically be picked up by the Trial Balance. Therefore, businesses must perform other controls in accounting. These include reconciling bank statements, verifying supporting documentation, good internal controls, verifying assets physically exist, and other accounting processes. This can allow businesses to ensure that they have accurate financial information.
Improving Accurate Trial Balances
To produce accurate Trial Balances, businesses can implement consistent bookkeeping processes. All transactions should have appropriate supporting documentation, and be recorded in the correct accounts to be transferred into the General Ledger. Accountants should also reconcile bank statements, investigate unusual balances, and ensure that journal entries have been properly authorized. Using reliable accounting software will reduce calculation errors. However, professional oversight is still required in accounting. If incorrect information is input into an accounting system, misleading information may be produced in reports. In addition, regularly training staff, separating financial responsibilities, and carrying out regular internal audits will improve accounting controls. All of this practice allows businesses to spot discrepancies early and reduces the chance of incorrect financial reporting.
Conclusion
Trial Balances are an important part of accounting. By providing a summary of account balances in the ledger, and ensuring that Debits and Credits are equal, they allow businesses to produce reliable financial statements. In different stages of the accounting process (unadjusted, adjusted, post-closing), Trial Balances allow accountants to find mathematical discrepancies, investigate posting errors, and correct any mistakes in the accounts. However, just because a Trial Balance has been balanced, this doesn’t mean that all transactions have been accurately, completely, or correctly recorded. Therefore, businesses must implement additional checks, keep appropriate documentation, and improve internal controls. Combined with these actions, Trial Balances can be an extremely useful tool within accounting. It can improve accuracy in financial information, increase transparency, and support informed business decisions.
Get more well researched information about Trial Balance in Accounting here.