Introduction
Credit risk assessment is an essential part of modern banking, in the past banks have used credit scores, employment history, income, security and repayment history to assess loan applications. Although this is very useful there can be cases where it does not show a full picture of the borrower’s financial situation. As everyone’s spending, income, debt, and commitments can change there are now more and more banks using Big Data Analytics in Credit Risk Assessment. This can help banks make more informed lending decisions, predict defaulters more accurately, and classify risk more effectively. Overall it will allow banks to offer credit to those who would have otherwise been turned down.
1. Borrower’s Financial History
By using big data analytics banks are able to look into the borrower’s financial background more fully. This means banks can look into years of financial data, this can include looking at their previous loans, bank statements, repayment history, income and what has gone on in their account. This helps lenders see how someone has been managing their financial commitments. If someone has good repayment habits and a reasonable amount of debt they could be seen as being financially responsible despite having a low credit score. Advanced analytics can be used to identify patterns in their financial history. This will help banks see if they are a high credit risk.
2. Borrower’s Income
Borrower’s income is one of the most important aspects banks look at. However just looking at a payslip may not give a true reflection of the borrower’s financial situation. With big data analytics banks can look at their income over a longer period of time. This can include looking at their salary, income from business, freelancing, commission and other sources of income. This can be helpful for those who are self-employed or working in informal sectors. By looking at how regularly they are earning money, how regularly they earn, seasonal changes and any fluctuation in income banks can get an idea of how much capacity they have to repay. This can help banks make more realistic lending decisions and reduce the chances of turning someone away due to their income.
3. Borrower’s Spending
Looking at borrowers spending can give useful information. By analyzing transactions banks can see how regularly they spend, how much they spend on discretionary items, lifestyle items and if there are any changes. If someone is regularly spending a large amount of their income on discretionary items they may have less money to pay back their loan. If they frequently go into their overdraft or take money out straight after getting paid they may be under financial pressure. By using big data analytics lenders can identify patterns. This gives banks a more realistic idea of how they spend their money.
4. Debt
Debt can have a big impact on a borrower’s ability to manage extra financial commitments. Big data analytics can help banks see what loans, credit cards, overdrafts, mortgages and other financial commitments they currently have. By looking at their financial history and credit report lenders can see how much debt they have altogether and how much income they have. This will give a clearer idea of their debt to income ratio. If they have a steady salary but several loans taking up most of their income they could be a large credit risk. By knowing what commitments they have before approving a loan banks can stop them from over borrowing, reduce the risk of default and set them a loan amount they can afford.
5. Repayment History
The repayment history of a borrower can give useful information. By using big data analytics banks can look at how regularly they repay, if they have missed payments, delayed payments, outstanding payments and how they have settled previous loans. By using analytical systems banks can identify if they have had issues repaying. This can include seeing how frequently they have had issues repaying. If they occasionally miss payments but have regular repayments they may have had a short term issue. Machine learning can help identify this by looking at repayment patterns across large data sets. This will help banks make more balanced lending decisions and identify responsible borrowers.
6. Bank Transactions
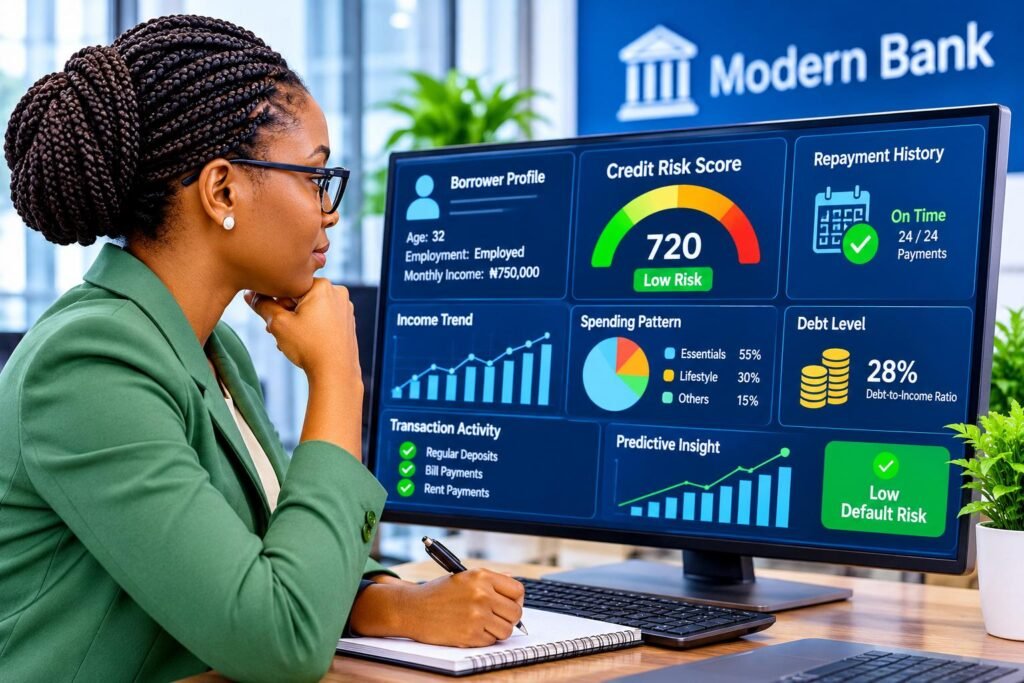
By looking at borrowers bank transactions banks can see detailed information on how they have been earning and spending money. By using big data analytics lenders can see how much they deposit, withdraw, transfer, pay bills, pay merchants and make regular financial commitments. This will help banks see if they have enough cash flow to repay their loan. If they are regularly depositing into their account from their business this could show they are financially active despite not having any conventional employment documents. If they are regularly paying their utilities and rent this can give more evidence they are responsible with their money. By looking at their transactions banks can get a fuller picture of their financial situation.
7. Predictive Analytics
Using predictive analytics can help financial institutions see how likely borrowers are to default on their loans. By looking at previous lending data, repayment history, income and other variables predictive models can identify patterns which are linked to previous defaults. This can help banks see how likely they are to have issues repaying in the future. If they have had a drop in their account balance, an increase in debt and irregular income this could show they are having financial issues. The predictive models will look at this and give an idea of the risk. This will help banks make more proactive decisions when making lending decisions. They will no longer be making reactive decisions and can identify early warning signs.
8. Machine Learning
Machine learning can help banks analyze complex financial data. By using machine learning algorithms banks can learn from previous lending data. This will help them identify borrowers with different levels of risk. Machine learning models can look at patterns between income, spending, previous defaults, account balance and debt to give a more detailed credit evaluation. As more relevant data comes in they can train the models and test them. This will help banks make more accurate risk assessments. However they need to regularly check the systems to ensure they are not making incorrect predictions, biased decisions and that they are keeping up with changes in financial situations.
9. Real Time Monitoring
Conventional credit assessments often rely on the financial information at the time of application. However borrower’s financial situations can change significantly after the loan has been approved. By using big data analytics banks can monitor their financial situation in real time. This can identify key changes in their financial situation. If they are suddenly depositing less into their account, using their overdraft more and having failed payments this could show they are having financial issues. This can help banks identify potential issues with repayments. It can also help with ongoing management of their portfolio. This will help lenders see any changes in their credit exposure.
10. Automate Risk Classification
Big data analytics can help automate risk classifications. This can group borrowers into different risk classes based on how likely they are to default. By using analytical models banks can group their customers into low, medium and high risk based on their financial information. This will make it easier for lenders to assess applications and set the right conditions. Those with steady income, reasonable debt and good repayment history could be offered better interest rates. Those with a higher risk could need further checks or a smaller loan. This will help save time when looking over large volumes of applications. However banks should still have the correct level of oversight.
11. Early Warning Signs
A key benefit of using big data analytics is identifying early warning signs. By looking at changes in account balances, unusual transactions, reduced income, increased borrowing and missed payments financial institutions can identify customers with worsening credit situations. This can be used to give early warning alerts. If someone has previously been regularly depositing but has started to have less income and increased overdraft use they may need to be monitored. By identifying this early banks can contact them, look at their repayments and offer the right financial help. This can help reduce loan losses, build relationships and improve the quality of their credit portfolios.
12. Offer Credit to More People
Traditional credit assessment methods can rule out those who do not have much borrowing history or enough documentation. This can include young adults, small business owners, freelancers and those in informal employment. Big data analytics can help banks look at alternative financial information. This can include verified cash flow, regular bill payments, business transactions and regular activity. This can give extra evidence they are responsible with their money. If someone owns a small business and has regular transactions they may have the ability to repay despite not having borrowed from a bank before. By using the correct alternative data financial institutions can look at more people and offer responsible credit to those who may not have been considered.
13. Reduce Losses
Defaulting can cause banks to lose a lot of money. This can include losing the principal, interest income, recovery costs and extra administration costs. By using big data analytics banks can reduce these losses by making more accurate assessments. This can identify those who are more likely to default based on their financial situation. The detailed assessments will help lenders make better decisions on whether to approve loans, how long to offer repayments for, interest rates and how much to lend. Banks can avoid offering large loans to those who already have significant financial commitments putting pressure on their income. They can also identify reliable customers who may deserve better lending terms. By using historical data and predictive models financial institutions can improve their lending strategies, manage their credit exposure and have healthier loan portfolios.
14. Personalized Decisions
Not all borrowers will have the same financial situations, income and repayment ability. By using big data analytics banks can make more personalized lending decisions. Analytical systems can look at how regularly customers earn, how they spend, their debt and repayment history to decide how much to lend them and how long to offer repayments for. If someone is a freelancer with irregular monthly income they may benefit from flexible repayment terms, whereas someone with a salary may be better with set monthly repayments. This can help make loans more affordable and reduce the chance of missed payments. It can also help banks create financial products to suit different customers.
15. Improve Compliance
Financial institutions must comply with regulations to ensure they are offering responsible lending. By using big data analytics banks can help keep their financial information organized, monitor their lending, identify unusual patterns and make more consistent assessments. Analytics can also help identify any suspicious transactions, potential financial issues and record what factors have influenced their lending decision. This is especially important if they are using automated models to make decisions. They must understand how their credit recommendations are being made. They must also have good data governance, privacy, validated models and regular audits. If used responsibly big data analytics will help improve oversight within the institution.
Conclusion
Big data analytics is changing the way credit risk is assessed. It gives financial institutions a more detailed understanding of the borrower’s financial situation. By looking at their financial history, income, spending, debt, transactions and repayment history banks can make more informed lending decisions. By using predictive analytics, machine learning, real time monitoring and automated risk classifications banks can identify potential defaulters, reduce losses and manage their credit exposure. It can also help them offer responsible credit to individuals and businesses who may have been overlooked. To ensure success they must have accurate data, good privacy, clear algorithms and the correct amount of oversight. As banking continues to change big data analytics will play an important role in creating more accurate, inclusive and sustainable lending systems.
Get more well researched information about Big Data Analytics in Credit Risk Assessment here.