Introduction
Money laundering and financial crime are still very much issues which banks and other financial institutions must deal with as criminals come up with new ways to hide illegal income. This may include use of many different accounts, cross border transactions, empty shell companies, fake transactions, and also what appears to be normal business operations. Also it is a challenge that traditional monitoring tools face in which they try to sort through large volumes of financial info in a short amount of time. But big data analytics puts in a better solution by looking at transaction history, customer info, payment patterns and other related data to recognize abnormal behavior. Also with modern Anti-money laundering AML systems banks are able to integrate automatic monitoring with in depth investigation which in turn detects what may be a threat, improves regulatory compliance, and at the same time protects the financial system from criminal action.
Analysis of Big Data in the Field of Financial Crime Prevention
Big in data analysis we see the collection, processing, and study of large complex data sets which in turn we use to identify trends, relationships, and unusual activities. In the field of financial crime prevention it is the role of banks to put these tools to work analyzing transactions which take place across accounts, branches, payment systems, and geographically. Instead of looking at each payment in standalone terms what we do is look at behavior over time and we put that in the context of what we know about the customer and what is to be expected of them. For example a transaction which on it’s own may not raise an flag may when put in a sequence of related anomalous activities such as many quick withdrawals, unconnected beneficiaries, or repeat transactions in high risk areas. By looking at the big picture in this way we are able to see patterns which may not present themselves in a0 simple manual review. Thus what we are doing is moving compliance teams from a reactive role in investigation to an active role in the early identification of what may be criminal activity.
The Issue of AML systems and KYC procedures
Anti-money laundering systems in which financial institutions use to identify, investigate and report transactions that may be related to criminal activity. We see in these systems the application of monitoring rules, risk indicators, and analytical models to customer and transaction data. Also their performance in great part is a result of Know Your Customer (KYC) processes which we see as the identification of customer identity, occupation, business activity, what is the scale of their typical transactions and where that money is coming from. Using that info banks can tell if in fact the real financial action of a customer is in line with what they have reported. For example repeat large scale international transfers from an account which has a report of average predictable income will require extra look into it. Also a greater degree of due diligence is to be applied to higher risk customers, political public figures and complex corporate structures. From exact KYC info accurate picture for the analytical systems is drawn out which in turn is able to put forward regular transactions as against possibly suspicious ones.
Transaction Pattern Analysis and Suspicious Behavior
Transaction pattern analysis is a tool which banks use to identify out of the ordinary financial activity by looking at payment amounts, frequency, timing, destinations, and relationships between transactions. We see that they also note what we may term as structuring or smurfing in which persons break up large sums into smaller transactions to avoid notice or reportable thresholds. Also they note the quick transfer of funds between accounts, very frequent large deposits in cash terms, sudden drops or increases in transaction volumes, and transfers that do not fit in with what went before in the account’s transaction history. Also machine learning models are used to create a behavioral profile which flags out large deviations for further look at. But also it is not the case that a strange transaction is the same thing as criminal action. That which appears to be a large transaction may in fact be a business which has a seasonal upturn in income, or an individual may receive an unexpected inheritance, so banks have to look at the overall picture of unusual patterns in the context of the customer’s situation, the purpose of the transaction and the support documentation before coming to a decision.

Network and Relationship Analysis
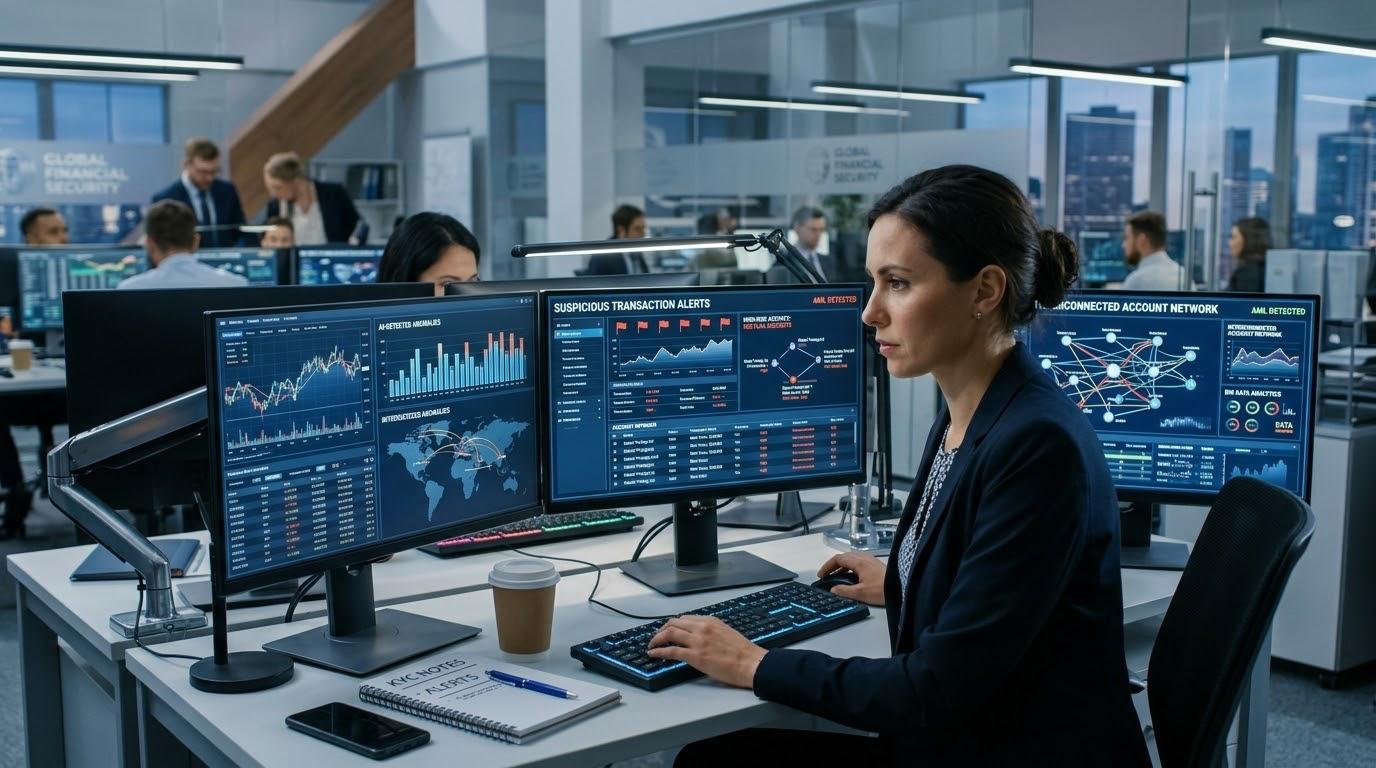
Criminals report to use many accounts, companies, intermediaries and jurisdictions to hide financial actions. We see that banks use network analysis which doesn’t always reveal itself in single transaction reviews. By looking at accounts, people, businesses, devices and beneficiaries as a whole network of connected entities we are able to see repeat relationships, circular flow of money, shared contact info, and coordinated movement of funds. For example may be that many businesses get money from diff users then pass it through a common go between before sending it to the same end user. Individually each payment may look ok but as a whole the relationship pattern may point to a large scale laundry operation. Investigators use these connections to trace money, to identify related accounts, and to get a better picture of the whole suspicious financial picture.
Sanctions Screening and Automated Compliance Monitoring
Sanctions screening is a tool which financial institutions use to identify customers, beneficiaries, and counterparties that may be caught by financial restrictions. Banks put forward relevant customer and payment info into authoritative sanctions lists and other required screening resources. Big data tools which we have at present improve this process by looking at large volumes of records in different systems and payment channels. Also we see that automated compliance monitoring looks at customer on board, account changes, transfers and other financial activities as they happen. Upon the appearance of a possible match or suspicious trend the system will put out an alert for review. For effective screening we see that which data is used needs to be updated often, that name matching is done accurately and that we also handle issues of spelling variation and incomplete records. Also banks have to play by the books in terms of what to do with transactions which may be delayed, rejected, frozen or sent up the chain for more review.
How Data Analysis is used to Prioritize Cases.
Financial institutions can see a large volume of watch lists which in turn overloads compliance teams’ attention they are unable to look into each issue with the same sense of urgency. We see that big data analytics play a role in which they pay attention to issues like transaction size, customer risk ratings, past reports of suspicious activity, geographic location of the transaction, and also the connection to very risky entities out there. Also we have very advanced systems which put together many different indicators which in turn put out which issues require that immediate attention. Then investigators get in and they look at account history, related transactions, customer documents, and also network connections through what we may term as integrated case management tools. This does in fact improve resource allocation and may also see a drop in the time it takes to identify very serious issues. At the same time though risk scores are a guide and not a determination. Human reviewers must still see how an alert came to be and go over the available info before they decide if some sort of action is in order.
False Positive Cases and the Role of Human Analysis
False outlays which in fact turn out to be true negatives are what we see when good transactions are put into the suspect pile. They come from very strict watch lists, lack of full customer info, out of date risk profiles, or models which don’t include normal financial behavior in their set up. Large number of false positives raise investigation costs, delay which should have been processed payments, also cause compliance officers to burn out. Banks may see results improve by fine tuning watch list criteria, updating customer files, in including relevant context info, and also by regularly putting model performance to the test against what the investigators do. At the same time which we try to reduce the numbers of these false reports we must not at the same time reduce our ability to find out true positive criminal activity. Human input is still very much a requirement because the machines may not get the very unusual but in fact legitimate transactions, also may not notice the fine detail. Investigators should look at the back up info, ask for more if they need it, document what they are thinking, and pass on to the next stage when they have reason to.
Regulatory Obligations, Data Governance, and Privacy
Banks are to comply with anti-money laundering laws, regulatory orders, sanctions requirements and data protection rules. In Nigeria the Central Bank of Nigeria issues out supervisory guidance related to anti money laundering and countering financing of terrorism which other regulatory bodies also play a role in. Based on the situation financial institutions may have to keep records, do customer due diligence, report suspicious transactions, and work with authorized investigators. Strong data governance which sets out clear rules for data quality, access, retention, security, and accountability supports these requirements. Also banks should protect sensitive customer info via appropriate encryption, access controls, audit trails, and secure data sharing which also includes monitoring of analytical models for issues, bias, and drop in performance. Also key to this is that data governance which is put in place is reliable and that financial crime detection is at all times effective, proportionate and legal.
Challenges and Future Developments
Although we see value in what big data analytics brings to financial crime prevention efforts it is also true that its implementation is far from seamless. Banks may have legacy systems which use different formats at which issue when trying to integrate data properly. Also issues of high cost, cyber risk, and the lack of which specialized talent are put forward which in turn play into reduced analytical performance. Also what we are seeing is that criminals’ methods are always changing so in that context it is important for banks to update what models they use for detection as well as their monitoring approaches. We see in the case of artificial intelligence and graph analytics there is an opportunity to detect early on new threats while at the same time private tech which improves secure cross source analysis is also a possibility. But at the same time we tell that institutions go in to these new tech solutions with caution and to also perform due diligence and maintain that human element. Also we note the role that collaboration between banks, regulators, law enforcers and tech providers have in which they can put together better models to identify financial crime networks at the same time also being aware of legal and confidentiality issues.
Conclusion
Big data analytics has played a key role for banks which are aimed at detecting money laundering and other financial crimes. Through the use of transaction pattern analysis, KYC data, network analysis, sanctions screening, and automatic compliance monitoring banks are able to identify abnormal relationships and priorize investigations. What we see is that analytics put together such that they reveal ties between what may at first appear to be unconnected transactions which in turn allows investigators to look at financial activity in great detail. At the same time it is important to note that analytics do not by themselves put an end to financial crime. We see issues with false positives, criminal adaptation of methods, regulatory requirements, data quality issues, and privacy concerns which require constant attention. Best results are achieved by a combination of solid technology, good data management, trained staff, and in depth human investigation. When these components work as a team banks are able to improve financial integrity, do better at regulatory compliance, and also make it is a less attractive environment for criminals to use the formal financial structure.
Get more well researched information about Big Data Analytics in Money Laundering Detection here.