Introduction
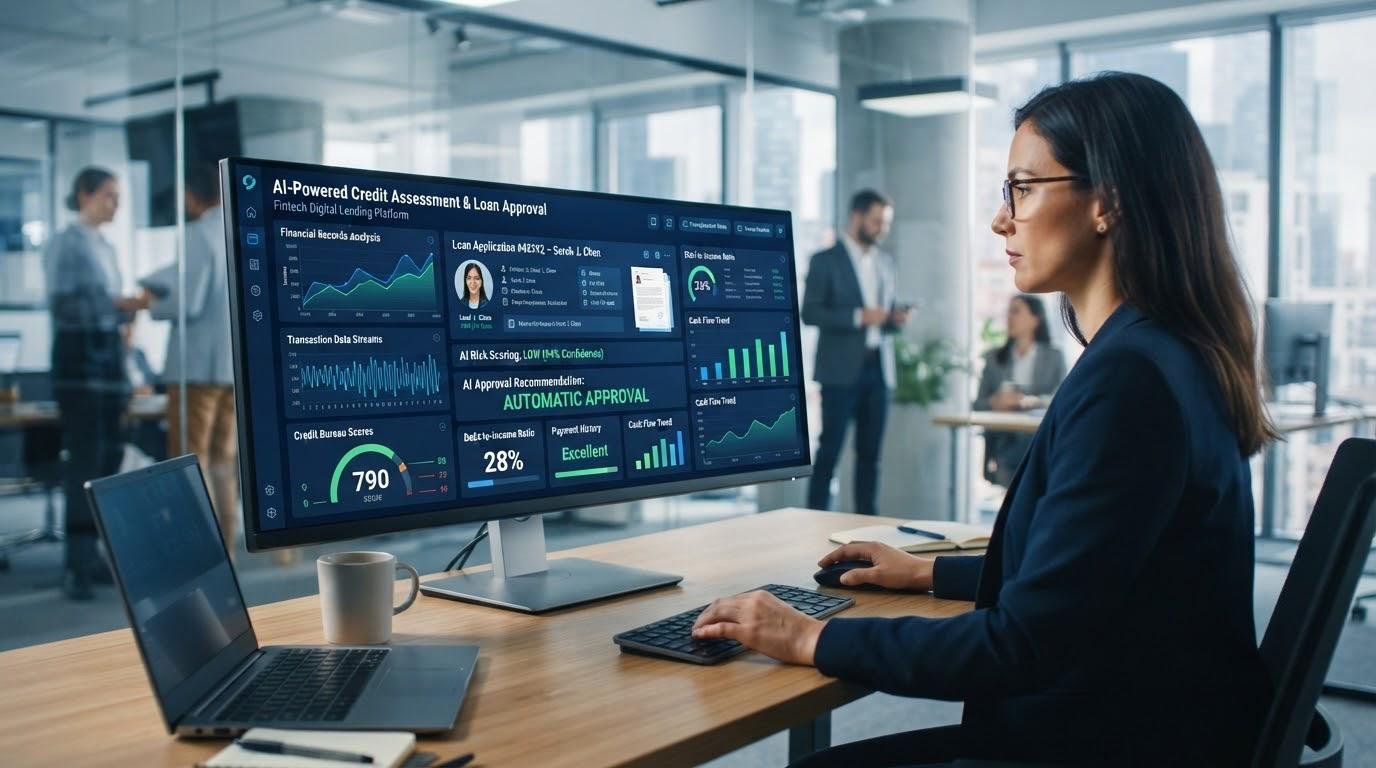
Traditionally, applying for a loan has entailed gathering financial records, credit histories etc. and waiting until a lender would take a look at the details. In part, artificial intelligence is transforming this process by making it faster and more consistent for financial institutions to sift through vast quantities of data to come up with an analysis. The question of how algorithms can assess financial histories is particularly significant as lenders increasingly rely on automated systems to look for patterns relating to the ability to pay back a loan, financial stress, and credit risk. Deloitte: AI and automation in finance. AI can read structured financial data as well as approved alternative data, and make decisions that used to have to be made manually with a lot of time. But, automated lending is not just about letting the software to approve or deny loans. Fairness, explanations, privacy, data quality, security and impacts of wrongful decisions are also critical aspects of effective systems.
How AI is helping to Achieve Modern Credit Scoring
Traditional methods of credit scoring typically involve factors like repayment history, amount owed, credit history, income and past borrowing activity. These and other variables allowed by the rules can be analyzed using AI-based assessment through statistical and machine-learning techniques developed to look for credit outcome relationships. Rather than being based on a set of static rules, a machine-learning model can learn from past examples and predict the probability of events like on-time payments or defaults. The model can include transaction patterns, cash-flow information, employment or income information, and other pertinent information, depending on the institution and pertinent requirements. The objective is typically to enhance the capabilities of an existing credit assessment by introducing analytical techniques not to eliminate the existing controls.
Using Financial History and Transaction Patterns to Analyze
AI can review financial history and identify patterns in how funds have been handled in the past, which can be crucial for determining whether an applicant is a suitable candidate. Financial history is important in determining whether or not an applicant is a suitable candidate, and AI can process this information at a scale that would be difficult to do manually for each application. Algorithms can be used to analyze repayment history, balances, income volatility, spending habits, account deposits, and other patterns in cash flow. For instance, a system might be able to determine if income is consistent or not, if expenses tend to be more than the income or if the debt payments seem reasonable for the amount of income. Transaction analysis can also help to detect changes that require further investigation that include a sudden drop in income or other odd behavior. The signals should be read in the context of the appropriate rules and as a sign of creditworthiness or risk, not as automatic facts.
Role Played by Alternative Data
Alternatively, data can be defined very generally as information that can be used to supplement the information contained in a credit report if it is legally allowed, relevant and responsibly collected. This may include verified cash flow data, pattern of recurring payments, employment data or other financial data which reflects an applicant’s ability to fulfill their debt obligations, depending on the jurisdiction, lender and product. For those with fewer traditional credit histories, alternative data could help make sense of their financial situation because a thin credit file may not sufficiently explain their financial situation. AI can analyze several allowed data points and uncover trends, which can be missed by humans. But this does not assure that more data will lead to better decisions. Each source needs to be considered in terms of accuracy, relevance, lawfulness of access and representativeness and appropriateness of the decision.
Automation of Loan Application Process
While AI doesn’t replace the hands-on aspect of the loan application process, it can streamline various parts of it. An automated application can perform the following: gather data; evaluate documents; validate and confirm the data entered; validate missing data; perform financial calculations, ratios, etc.; route applications based on a set of predetermined criteria. Machine-learning tools can be employed to determine which applications to review further if there are missing or unusual details. When it comes to simpler applications, automation can minimize repetitive admin tasks and speed up the time from application to initial decision. More complicated cases can be referred to human workers who will look into different factors. This can lead to the scaling up of lending operations, without losing out on the opportunity for professional judgment, as per policies and requirements applicable to the institution.

Benefits of Faster and more Consistent Decisions
One of the biggest advantages of using artificial intelligence for credit checks is that it can help speed up the process. A system can process large volumes of structured data in a short amount of time, which means that applicants won’t have to wait as long to get their applications processed, and lenders will be able to take on more applications without having to add manual tasks in the same proportion. Also, automation can help to improve consistency as it can use programmed procedures for similar applications and not just rely on the employees to complete the repetitive calculations. All decisions are not guaranteed to be correct or fair since there is a possibility of weaknesses in the underlying data and in the model. However, a standardized processing may facilitate the monitoring of processing by institutions and allow them to recognize any abnormal variations of the processing results. AI can thus be used to boost efficiency and aid lenders to handle the increasing number of digital applications.
Risk of Algorithmic Bias and Concerns about Fair Lending
One of the main issues is that an AI system can replicate or reinforce inequitable trends in the past. If history of lending practices had been unfair or credit had been limited, then the algorithm developed based on this data could discover patterns that lead to undesirable results. Bias may also occur with seemingly gender-neutral variables serving as proxies for protected characteristics, and when there are significant differences in the extent of data available for each group. The technical correctness of a model is not sufficient proof of suitability of the lending results. Financial institutions should have procedures in place to test models, assess related outcomes, track results post deployment, and explore unanticipated outcomes. The provisions of the fair lending policy and any other relevant regulations should be kept within the governance framework.
Why Explainability Matters
When loan approval is on the table, it can make a big difference for the borrower, especially when financing a home, a vehicle or other major expenses, such as college and business ventures. That’s why applicants and regulators might require relevant information on the rationale for a decision. Machine-learning models, especially those that are advanced, can be hard to understand since they use multiple variables and complex relationships. Explanations are not just about presenting technical outputs of models, but can be presented and useful through the use of explainability tools which can help identify influential factors. Lenders also must have processes to address any disputes, to correct any inaccurate information and where necessary, review any decision. Explainability is thus related to accountability: institutions require sufficient understanding of the system to oversee, explain and correct their actions when necessary.
Data Protection, Privacy
When using AI-supported lending, there is a major concern for privacy, as a lot of information, especially personal and financial details may need to be shared with the AI. Institutions should gather and process data for legitimate reasons, restrict access to authorized data and systems, ensure confidential access to data, and comply with financial privacy laws. Alternatively, when using alternative data, these responsibilities are even more critical since it’s possible that an applicant will expect that not all the digital signals that are available will be considered when deciding on credit. Collection can be avoided by implementing data minimization and purpose limitation. Financial data can also be important for financial criminals and is therefore important to have robust cyber security measures in place. Therefore, privacy should be taken into account from data collection to storage, model development to deployment, monitoring and retention to deletion in the process of the AI lifecycle.
Importance of Data Quality
The information fed into AI systems is what they are built on and thus affects their reliability. A model’s performance can be impacted by inaccurate income data, out-of-date credit data, duplicate transactions, missing data, or inconsistent data sources. There are data issues that need to be fixed that a sophisticated algorithm can’t do automatically. Financial institutions must have processes to check information, detect anomalies, track data quality and put corrective processes in place to resolve data errors. They also have to pick out real financial risk from unusual, but valid situations. A short-term change in cash flow, as occurred here, can take different forms and shouldn’t necessarily be seen as a sign of a longer-term cash flow issue. Through regular testing and monitoring, situations can be identified where the performance of the model is altered due to economic, applicant and/or source data changes.
Human Oversight and Responsible Automation
While AI can handle a lot of the credit evaluation process, there are instances where human involvement is crucial, such as cases with uncertainties, atypical situations, disagreements, or even potentially significant inaccuracies. Human reviewers can consider information that may not be captured in a model and decide if the result from the automated process needs to be further investigated. Oversight does not imply a direct reversal of all automated decisions; instead, it is about making sure the automation decisions are correct, thereby reducing the potential for a loss of efficiency and consistency. Rather, institutions can set up guidelines for escalation, quality assurance reviews, model monitoring, and reconsideration processes. Oversight staff also must have enough knowledge of technology to identify its boundaries and pose queries about items that do not seem right. This will be a way of using AI as a decision support system, but without compromising institutional accountability.
The Future of AI in Lending
As financial institutions continue to strive for quicker loan processing, better risk management, and enhanced customer experience, AI is set to play a vital role in digital lending. Potential systems could be a blend of traditional credit data, documented cash-flow and fraud detection, as well as more advanced predictive models. But, technological development will not eliminate the need for governance. Institutions will require keeping track of models as economic conditions evolve, audit data sources, examine for unfair outcomes, safeguard personal data, and have processes and protocols to intervene with humans. Financial institutions and regulators can also further evolve the expectations around automated decision making, transparency and consumer protection. The progress will thus not only be achieved through the development of increasingly sophisticated algorithms, but also through the creation of testable, understandable, monitored and correctable systems.
Conclusion
AI can transform the credit scoring and loan application process by enabling financial institutions to analyze financial records, transaction trends, income data and more, which are considered acceptable data points, in more time and with more volume. It can be used to assist in automatic application examinations, detect credit risk patterns and aid lenders in making routine decisions in a more consistent manner. While these will help to make things easier and quicker for some applicants, they won’t solve the issue of responsible lending. Actively managing algorithmic bias, explainability, privacy, data quality, security, and incorrect decisions are all necessary. Alternative data can be used to enhance information available for assessment, but must be relevant, legal, accurate, and managed appropriately. The most responsible way to do this is to have a good combination of useful AI features with good controls, human oversight, decent processes and ways to rectify errors.
Get more well researched information about AI in credit scoring and loan approval here.