Introduction
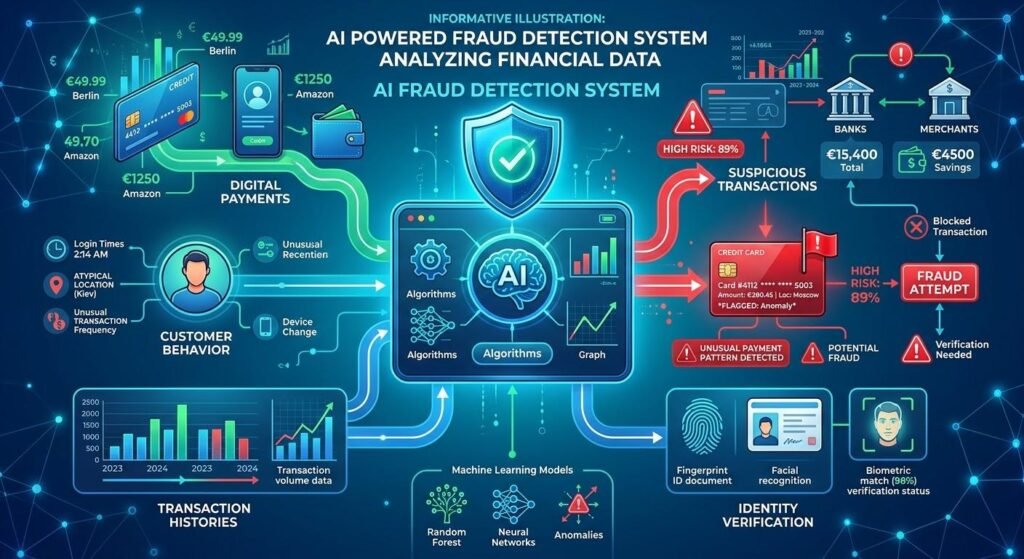
Financial fraud is growing in complexity as we see an increase in online banking and digital payments. Outfit criminals are using stolen information; they are hacking payment systems, creating fake IDs, and getting into financial accounts via cyber-attacks. Presently used fraud detection which does for the most part rely on set in stone rules and manual investigation are a challenge against very dynamic issues. What we are seeing is that Artificial intelligence, machine learning, and big data analysis are what is at the fore front of how financial institutions are improving in their fraud detection and prevention. These tech’s are used to study large sets of financial data which in turn helps banks to recognize what is out of the ordinary and to that which is suspicious very fast. Also with real time transaction monitoring financial institutions are able to look at each transaction as it happens which in turn allows them to put a stop to what looks like a fraud attempt before it causes great loss.
AI and Big Data in the World of Fraud Detection
Big data is what we get from financial transactions, customer interactions, digital banking services, payment networks and so on. We use AI to go through this info and find out which patterns and relationships may point to fraud. Machine learning within AI allows us to look at past transaction records to improve our which of detecting off the mark activities as we get more info. For example a bank will look at past fraud cases to identify what is it is that goes along with unauthorized transfers. As we see that same telltales in new transactions we put together a risk score and we pass it on for more look over. By using these techs together financial institutions get a better picture of fraud risks then what single security check can give but it is also true that for them to work well we need good data, proper models and constant review.
1. Real Time Transaction Tracking and Identification of Suspicious Payments
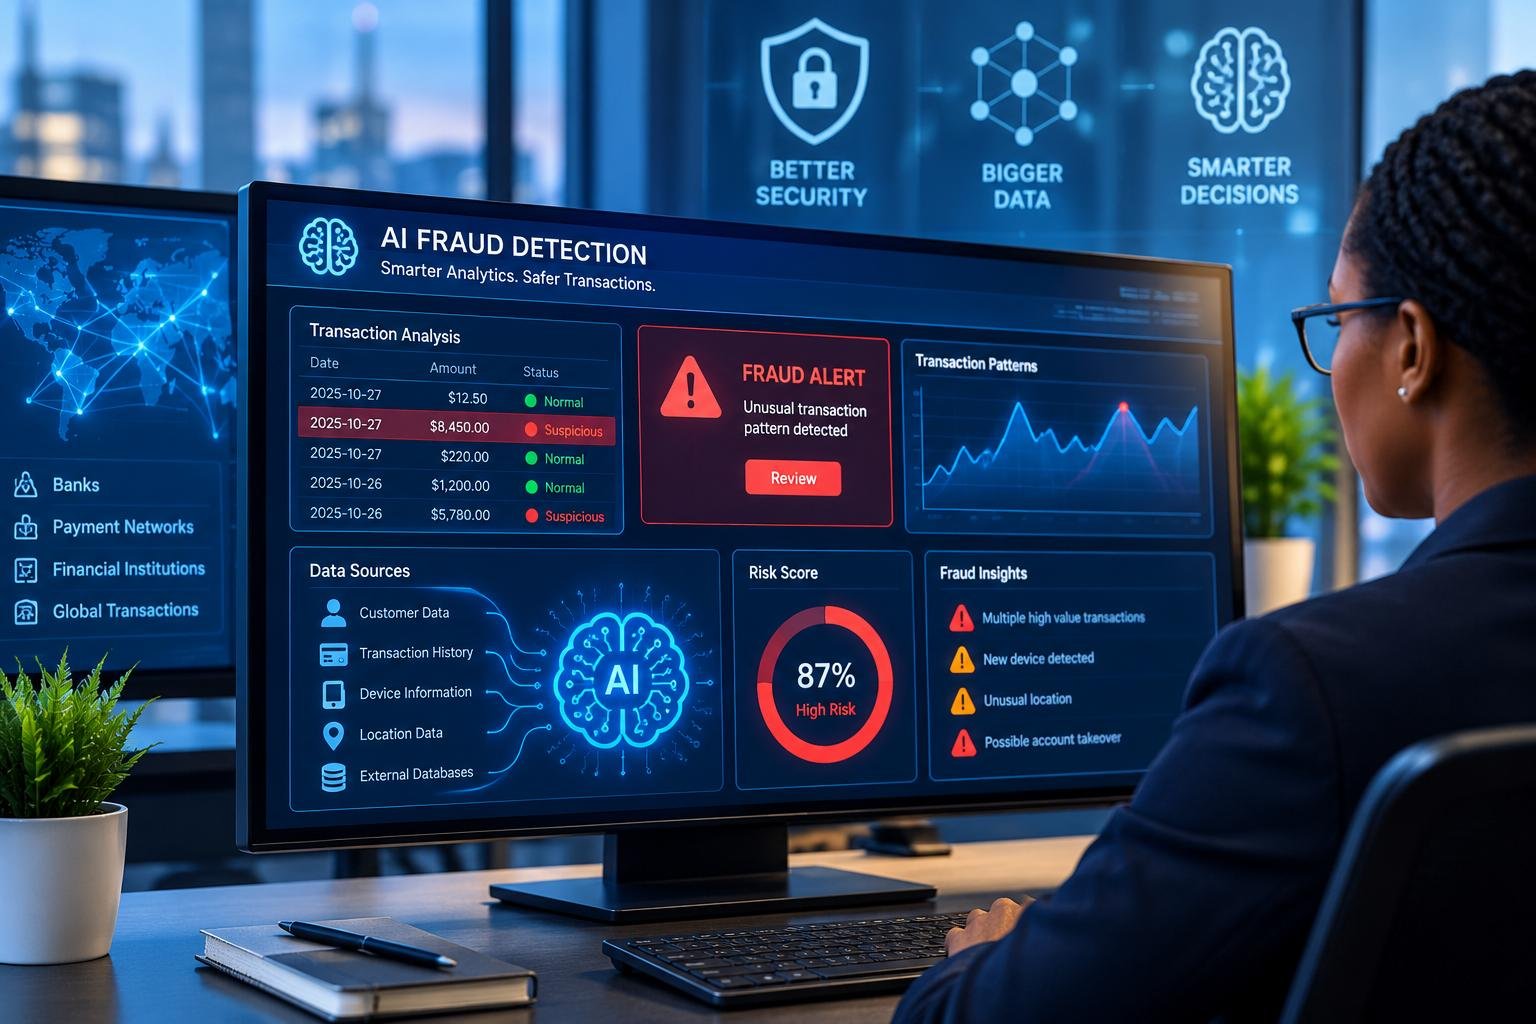
Real time transactions monitoring which financial institutions use as customers initiate them. AI powered systems look at variables like the transaction size, how often they occur, info of the payee, geographic location, device used, and the customer’s usual spending trends. When a transaction changes greatly from what we know of a customer’s past behavior the system will flag it for more review or block it out right away based on the level of risk which is assessed by the banks’ policies. For example a customer which generally does small scale local payments may out of the blue do very large volume of high value payments to unknown foreign accounts. That the system will see as out of the norm and will put through a security check before green lighting any further action. Also in real time the financial institutions are able to react immediately to these issues as they come up instead of after the fact, so they in turn have less chance to stop the crooks from moving funds into other accounts.
2. Behavioral Analytics and Anomaly Detection
Behavior in the use of financial services is what behavioral analytics looks at. AI systems track what are normal customer actions, for example they will note in which time frame logins take place, what the transaction amounts are, what are the spending categories, where transfers go, and which devices are used. When an account does something out of the ordinary the system will flag it as a possible security issue. For instance if we see that a person usually logs in from home and suddenly logs in from a public library and also does an unusual large transfer right after that we may have a case of a breached account. Also it is not true that any atypical action means fraud. Our customers may do out of the ordinary things like travel or buy a very expensive item which has nothing to do with fraud. What works best is looking at many different indicators at once instead of one at a time. That way financial institution is able to tell the difference between possibly illegal behavior and normal changes in a customer’s life.
3. Detecting Anomalies and Unusual Payment Patterns
Anomaly detection is the process of putting out of the ordinary transactions or activities which do not fit what is expected. Machine learning models look at millions of transactions to report on what traditional rule based systems may not see. We see this in multiple transfers just under reporting limits, large jumps in transaction frequency, repeat payments to related accounts, and when money flows between accounts in strange ways. Also AI is looking at how customers, devices, merchants, and payment recipients interact with each other to find out which may be in a fraud network. These associations may present organized fraud which is carried out by many accounts that are used to move around money or to cover up where it comes from. Through analysis of the separate transactions as well as the large picture of payment relationships, financial institutions are able to put together very complex fraud patterns which are a tough task for manual checks to perform.
4. Identity Verification and Synthetic Identity Fraud
Identity verification is a also key area of play for AI and big data in financial crime prevention. In that field we see banks and other financial players implement auto systems which they use to compare ID docs, verify face shots, look at what is put forward by the customer and identify any issues at sign up. Also we have optical character recognition which extracts info from ID docs and within that the tech of facial matching and live detection which is used to determine that the person present is in fact the person in the picture as opposed to a photo or doctored video. These measures play a role in to which we see less impersonation and use of stolen IDs, which is a particular benefit when these controls are used in conjunction with trusted databases and other verification tools.
Synthetic identity fraud is a different issue in which criminals put together real and fake info to present a new individual that looks legitimate. They may present a real ID number with a made up name, fake contact info, or a bootstrapped credit history. These identities may be slowly built up over time before they are used to get loans, payment cards, or other financial products. AI we have is able to identify out of place info between applications, the same device IDs, repeat contact info, and also odd associations between accounts. Also big data analysis plays a role in putting together the picture of these separate indicators which in turn allows institutions to see what may be a fraud network instead of looking at each application in a vacuum.
5. Reducing False Fraud Alerts
One issue in fraud detection is we have a large set of legitimate transactions which end up being flagged as suspicious. We see too many false alerts which in turn increase investigation costs, delays payments; frustrate customers and puts pressure on fraud prevention teams. AI plays a role in solving this by looking at transaction context, customer history and many risk factors at the same time. Rather than flagging each high value payment we can look at if the amount is typical for that customer, if the receiver is known, and if the transaction is what we see from that customer in the past. Also machine learning models can be adjusted using results of investigations which in turn help them to better tell the difference between confirmed fraud and legitimate activity. We see also that risk based alert ranking which puts the most serious cases to the top of the pile for investigators to look at first. But at the same time we must not reduce false positive rates so much that we miss out on detecting real fraud, which is why it is important to measure not only detection accuracy but also the rate of fraud which goes undetected.
Challenges in AI-Powered Fraud Detection
Fraudsters are always changing their tactics in order to get past our security. They may use automatic processes, stolen access info, assumed IDs, or AI created material that makes fraud look real. As a result detection tools have to be updated often and put through tests as new threats arise out. Also key is the issue of data quality we may have full sets but if they are out of date, inconsistent, or incorrect our results will be too. If a model is trained on biased past reports or doesn’t include the latest fraud techniques it may break down. That is why financial institutions must put in strong data management plans, do regular health checks on models, and use past history which also includes present threat info. Also what we see as new patterns may not always be illegal activity — by sharing what we find with other trusted companies we can improve our chances of recognizing new schemes early.
Privacy, Security, and Human Oversight
AI in the field of fraud detection which has access to very private financial and personal info puts forth important issues of privacy and cyber security. Institutions must put in place proper access controls, encryption, and secure storage measures and at the same time be in compliance with relevant data protection laws. Also they should collect and retain only what is relevant for a given purpose and put in place clear rules which govern the use of that info. Human element is very much a part of the picture as automated systems may fall short of accuracy, may be hard to interpret, or may be affected by biased data. Also it is the role of the human investigator to look at complex cases, determine the context behind unusual transactions, and question machine based decisions when the facts point to a different conclusion. Also we must have in place for the customer the means to appeal a payment block or a contested account issue. By combining machine analysis with that of experienced human judgment we may achieve a better balance in the fight against financial crime.
The AI and Big Data in Terms of Fraud Prevention
The future of fraud detection will see more of a shift towards adaptive AI models, stronger identity verification, improved network analysis, and greater financial institution collaboration. We will see more of a blend of transaction info with device intelligence, behavioral data, and context in which the transactions take place in order to identify risks earlier. Generative AI may play a role in that it will sum up what is suspicious, present case info in an organized way, and put forth which transactions were flagged and why. Also we must be very careful with these to avoid inaccurate results and to protect customer info. Also financial institutions will require strong governance structures, regular independent review, and defined what each party’s role is with regard to customer funds. What we will see is that success in this area is not just about which tech you implement but that which you put in place is accurate, secure, transparent, and able to adapt to what criminals are doing.
Conclusion
Artificial intelligence and big data are transforming fraud detection for financial institutions which now are able to analyze transactions at scale, to identify abnormal activity, to verify identity, to see through synthetic identity schemes, and to react to suspicious payments much faster. We see that machine learning plays a large role in this by recognizing complex patterns and it adapt at a rapid pace to new risk issues also we have the use of contextual analysis to reduce non necessary fraud reports. That said tech isn’t a fix for all. In the case of poor quality data, privacy issues, growth of cybercrime, and non-accurate automated results which are still major problems. Fin institutions should put in solid data sets, which are constantly audited AI models, tight security measures, and input from human analysts in order to create effective anti-fraud systems. In a fine balance between pushing out innovative systems but also being held accountable is what will allow banks and other financial services companies to better protect their clients, to decrease financial damage and at the same time, foster the confidence in very digital financial systems.
Get more well researched information about AI and Big Data in Fraud Detection here.